group reporting
Goodwill Allocated to a Cash-Generating Unit That Includes a Foreign Subsidiary: How to Retranslate, Test, and Record the Impairment at Consolidation
When a group acquires a foreign subsidiary, goodwill must be retranslated at every closing rate, tested for impairment in the…
Why Xero Cannot Eliminate Intercompany Loans Between Two Xero Organisations and What Finance Teams Do Instead
Xero treats every organisation as an independent ledger with no native cross-entity consolidation layer, meaning intercompany loan balances between two…
How to Structure Intercompany Account Codes in a Group Chart of Accounts So Eliminations Run Without Manual Matching
Manual intercompany reconciliation at month-end is almost always a chart of accounts problem, not a process problem. This guide explains…
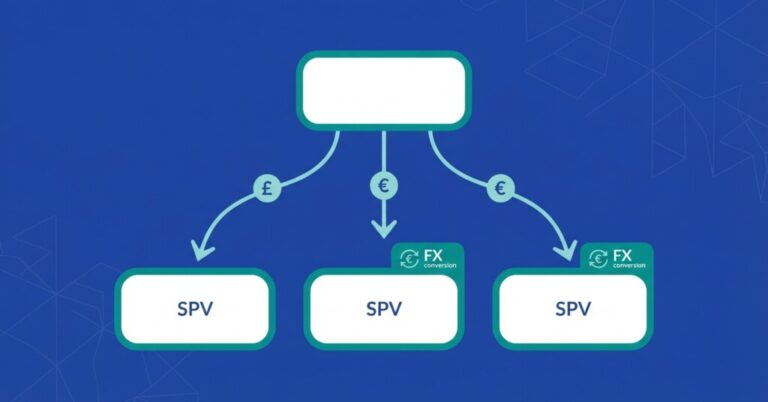
How to Consolidate a Multi-SPV Property Group When Each Vehicle Has Its Own Intercompany Loan From the Holding Company
Property groups structured through special purpose vehicles face a layered consolidation challenge when every SPV carries an intercompany loan from…
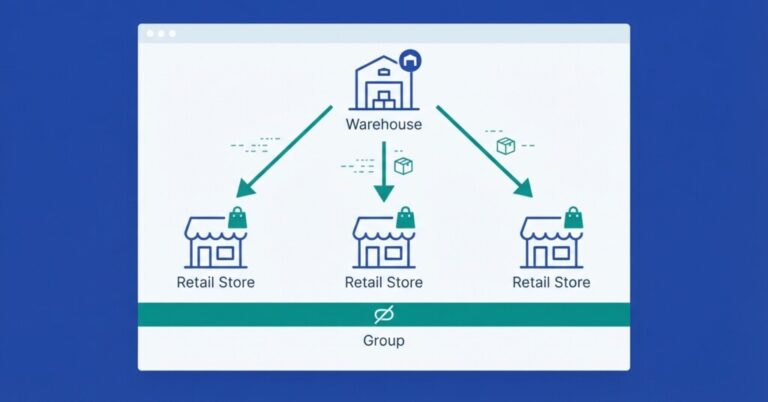
How to Eliminate Intercompany Stock Transfers Between a Central Warehouse Entity and Retail Store Subsidiaries
When a central warehouse entity distributes stock to retail subsidiaries, intercompany transfers must be eliminated at consolidation to remove inflated…
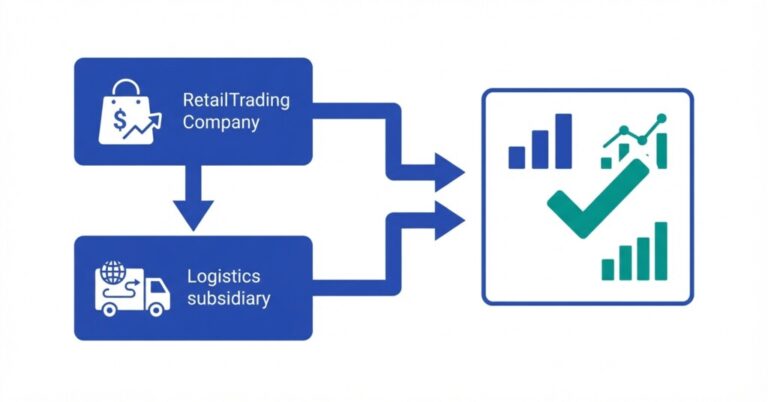
How to Eliminate Intercompany Fulfilment Fees When Your E-commerce Group Uses an In-House Logistics Subsidiary
E-commerce groups with an in-house logistics subsidiary face a persistent consolidation challenge: intercompany fulfilment fees inflate both group revenue and…
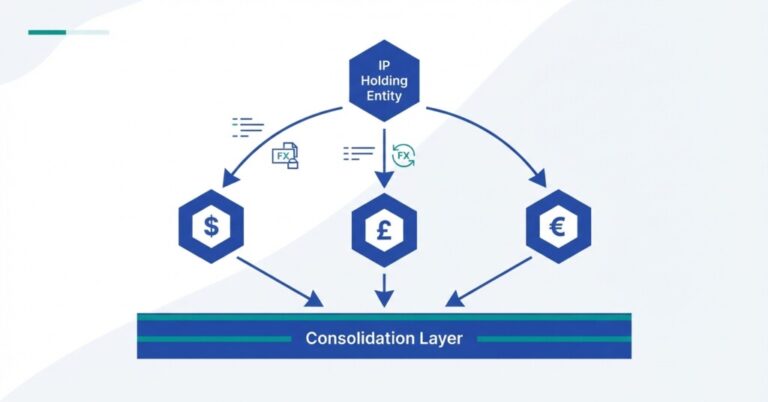
How to Eliminate Intercompany SaaS Platform Fees When the IP Entity and the Operating Subsidiaries Are in Different Currencies
When an IP entity invoices SaaS platform fees to operating subsidiaries reporting in different currencies, simple journal reversal is not…
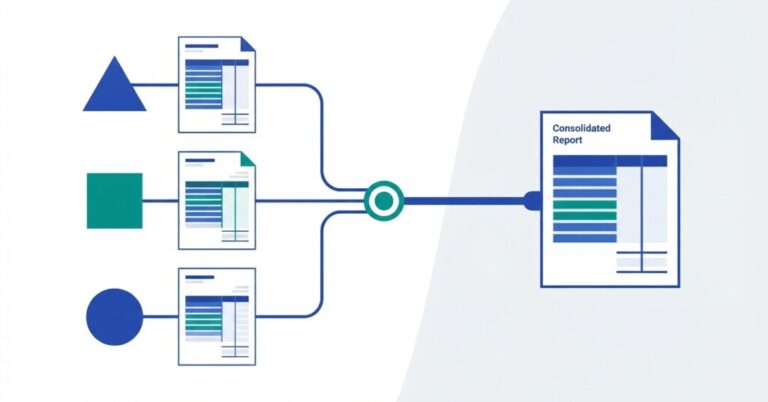
How to Produce a Consolidated Trial Balance From Multiple Xero Organisations When Each Entity Uses a Different Chart of Accounts
Finance teams managing multiple Xero organisations often face a three-part challenge when producing group accounts: mismatched charts of accounts, intercompany…
IFRS vs FRS 102: How Goodwill Accounting Differences Force Different Consolidation Adjustments in Mixed-Standard Groups
For SME finance teams managing mixed-standard groups, goodwill is one of the most consequential differences to reconcile at consolidation. FRS…
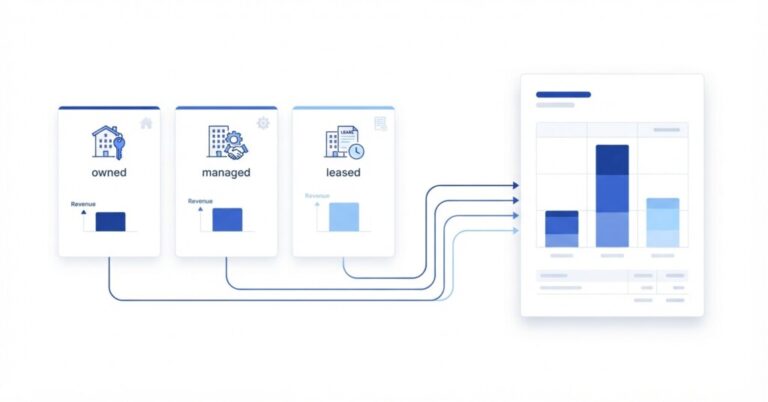
Consolidated Revenue Reporting for a Hotel Group With Branded, Managed, and Leased Properties: Why Each Model Produces a Different Group P&L
Branded owned, managed, and leased hotel properties each produce a structurally different P&L at entity level. When consolidated into a…