business combinations
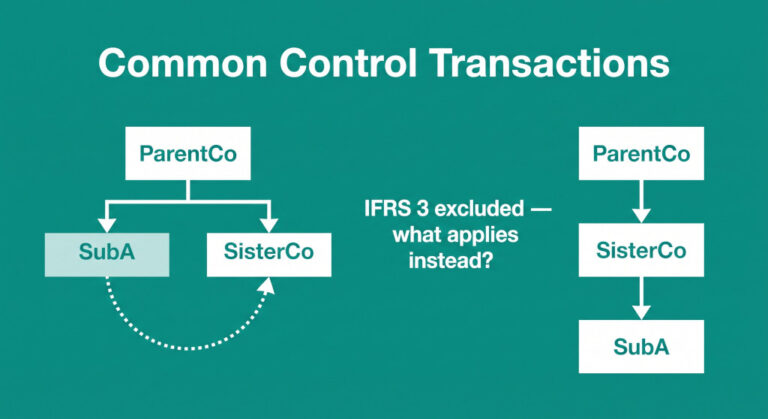
Intragroup Restructuring: How to Account for Common Control Transactions When IFRS 3 Doesn’t Apply
David had been CFO of the retail group for four years when the board approved a restructuring. For commercial and…
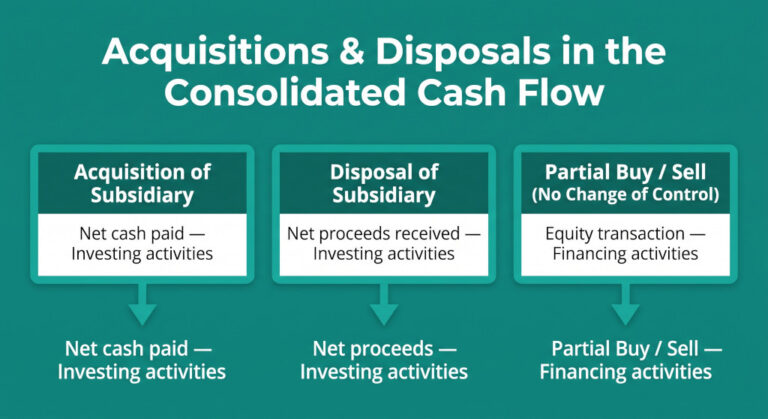
Acquisitions and Disposals in the Consolidated Cash Flow Statement
Daniel’s group had a busy year. In March, it acquired a software business for $3.2 million — $2.5 million paid…
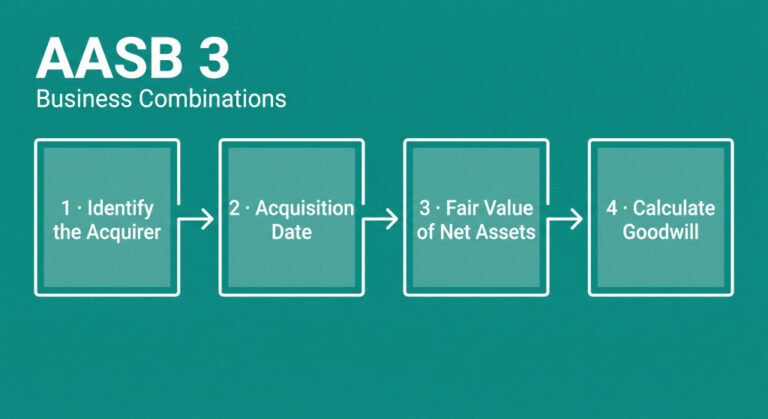
AASB 3 Business Combinations: A Practical Guide for Australian Multi-Entity Groups
When Sophie’s Melbourne-based consulting group acquired a smaller competitor for $2.8 million, the deal took six months of negotiation and…
US GAAP Business Combinations: A Practical Guide to ASC 805 for Multi-Entity Groups
The deal closed on 1 March. A US-based professional services group had acquired a 75% controlling stake in a regional…
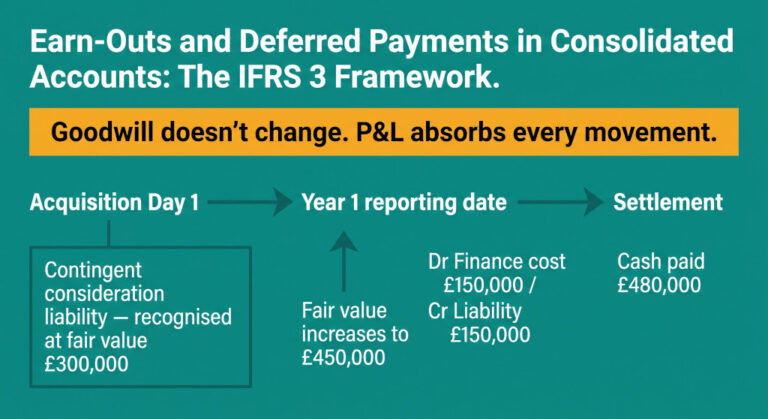
Contingent Consideration in Group Consolidation: Why Earn-Outs and Deferred Payments Look Different in Your Consolidated Accounts
When a group acquires a business, the consideration paid is rarely a single clean cash figure. Most acquisitions include some…
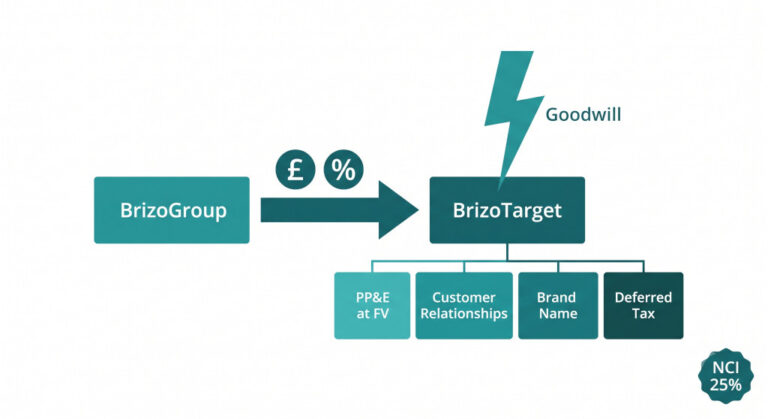
IFRS 3 Business Combinations: A Practical Guide for Multi-Entity Groups
Every consolidation begins with an acquisition. And every acquisition governed by IFRS starts with IFRS 3 Business Combinations — the standard that…
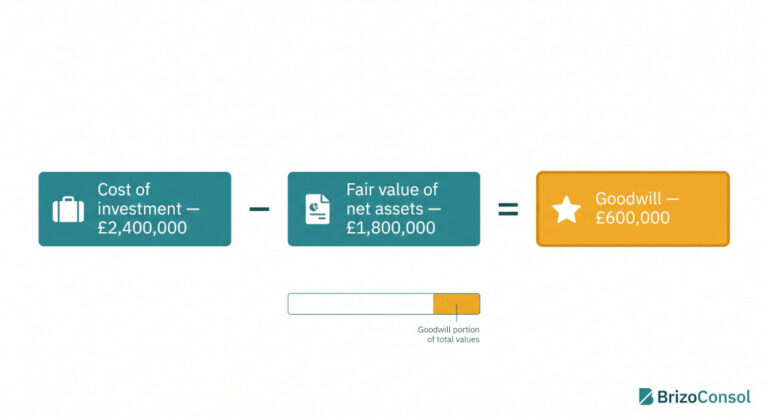
Goodwill in Group Consolidation: Calculation, Impairment, and Common Errors
Of all the numbers that appear on a consolidated balance sheet, goodwill is typically the one that generates the most…