UK GAAP
Guides to consolidation and financial reporting under UK GAAP, including key differences and implementation considerations.
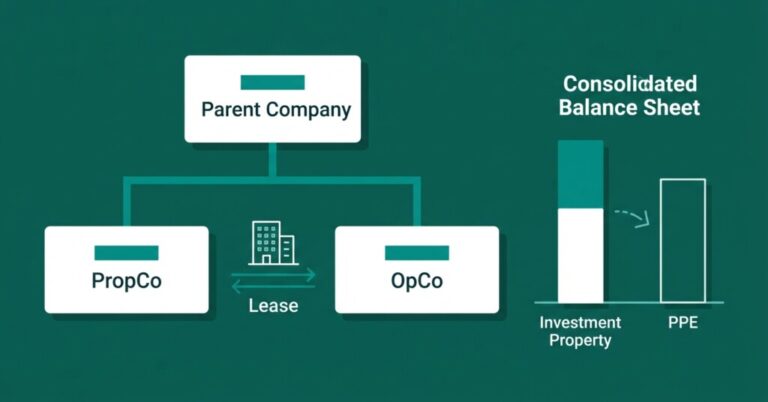
IFRS vs FRS 102: How Investment Property Accounting Differences Force Different Consolidation Adjustments When a UK Subsidiary Holds Group Real Estate
When a UK subsidiary holds property leased to another group entity, the accounting standard it applies — FRS 102 or…
IFRS vs FRS 102: How Goodwill Accounting Differences Force Different Consolidation Adjustments in Mixed-Standard Groups
For SME finance teams managing mixed-standard groups, goodwill is one of the most consequential differences to reconcile at consolidation. FRS…
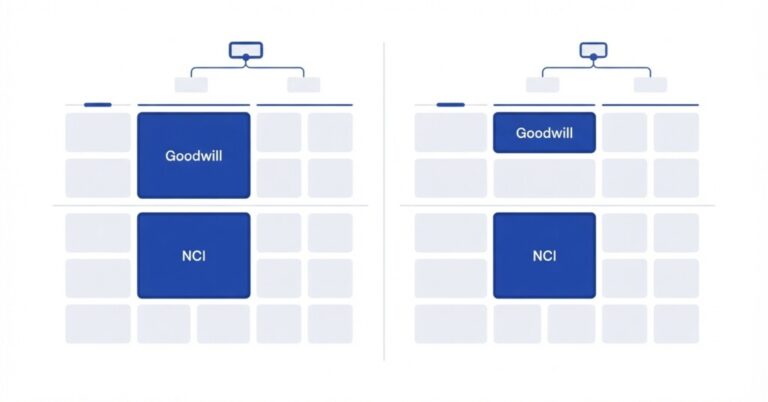
IFRS vs US GAAP: How NCI Measurement Differences Change Your Consolidated Balance Sheet
IFRS and US GAAP treat non-controlling interest measurement differently at acquisition date, and those differences compound across goodwill calculations, equity…
IFRS vs AASB: Key Differences That Affect Multi-Entity Group Consolidation in Australia
IFRS and AASB standards are closely aligned, but the differences that exist carry real consequences for multi-entity consolidation in Australia.…
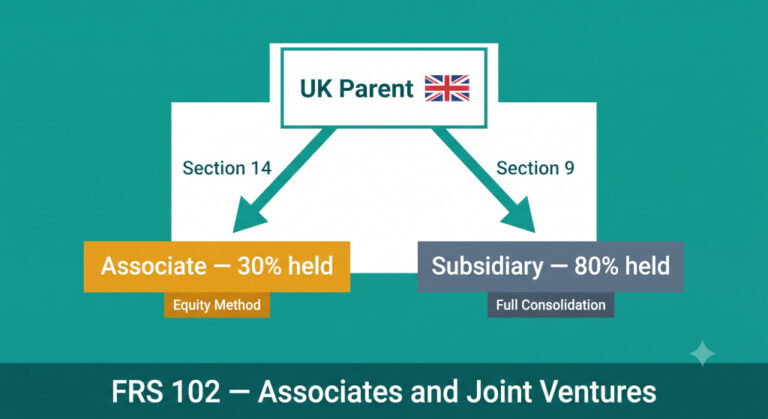
FRS 102 Associates and Joint Ventures: The Equity Method for UK Multi-Entity Groups
A UK manufacturing group held a 35% stake in a specialist components supplier for eleven years, accounting for its share…
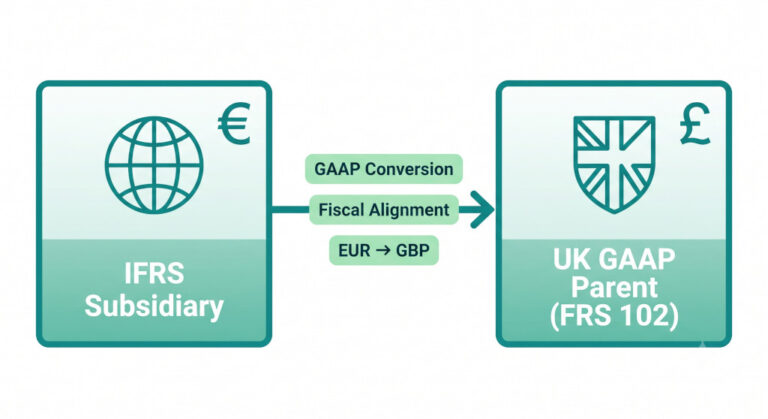
How to Consolidate an IFRS Subsidiary into a UK GAAP (FRS 102) Parent: Journals, Fiscal Periods, and Currency Translation
UK groups that have grown through acquisition — particularly those with European or international subsidiaries — often find themselves in…
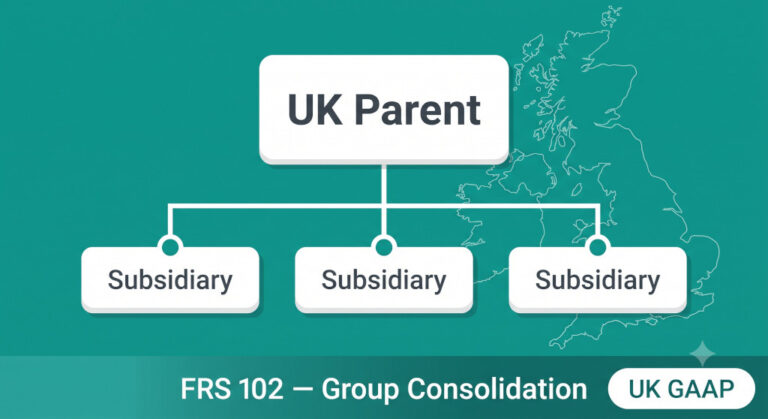
FRS 102 Consolidation: A Practical Guide for UK Multi-Entity Groups
The holding company had been incorporated two years earlier to sit above three trading subsidiaries, and the group’s accountants had…
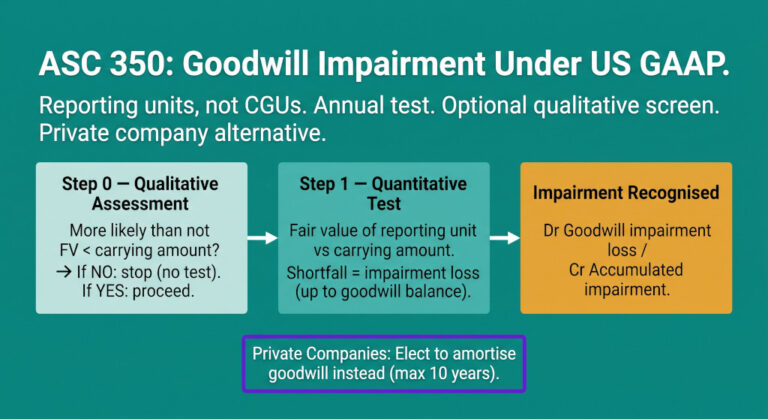
Goodwill Impairment Under US GAAP: How ASC 350 Works and What It Means for Multi-Entity Groups
Goodwill impairment testing under US GAAP is governed by ASC 350-20 — a framework that differs from the IFRS approach…
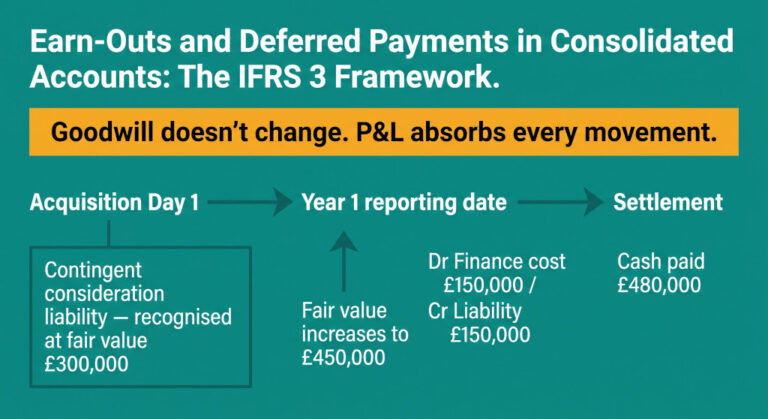
Contingent Consideration in Group Consolidation: Why Earn-Outs and Deferred Payments Look Different in Your Consolidated Accounts
When a group acquires a business, the consideration paid is rarely a single clean cash figure. Most acquisitions include some…
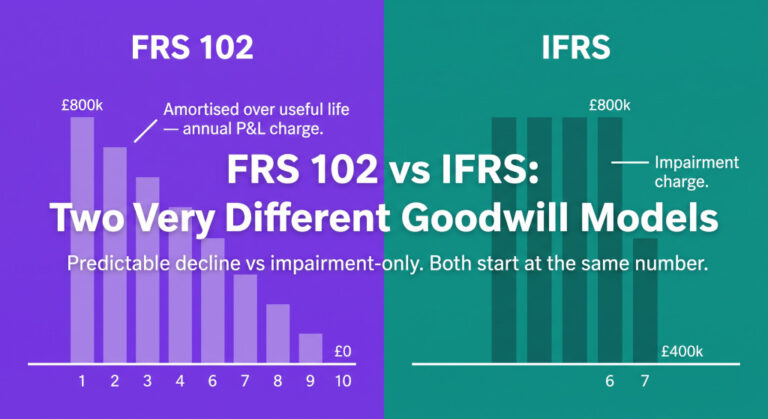
FRS 102 Goodwill Amortisation: How UK GAAP Groups Account for Goodwill Differently From IFRS
Goodwill is one of the most significant balance sheet items in any acquisitive group, and the accounting treatment depends entirely…