Currency Translation (CTA)
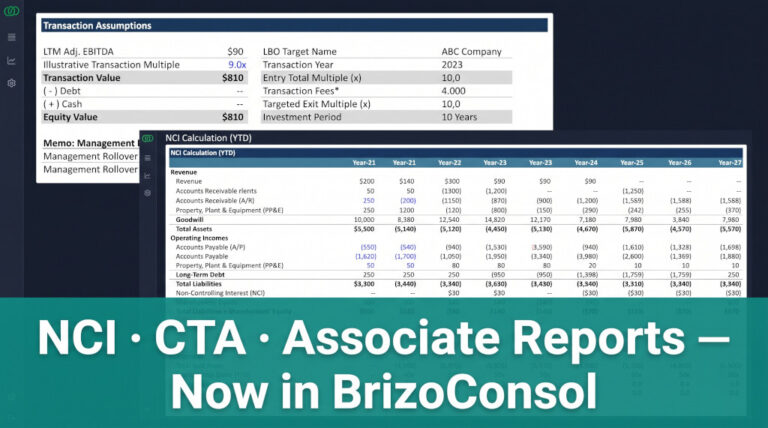
NCI, CTA, and JV/Associate Reports: Audit-Ready Consolidation Workings Now Built Into BrizoConsol
Audit season for group accounts has a predictable shape. The auditors ask for the consolidation workpapers. The group controller produces…
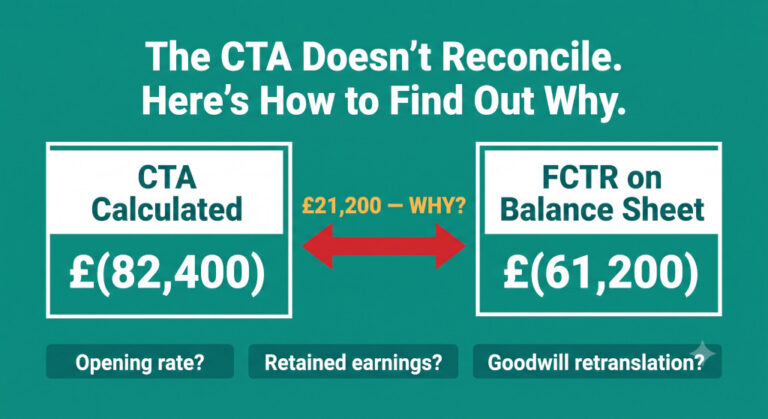
Why Does My CTA Not Reconcile?
Anna had followed the three-rate rule correctly. P&L at the average rate, balance sheet at the closing rate. She had…
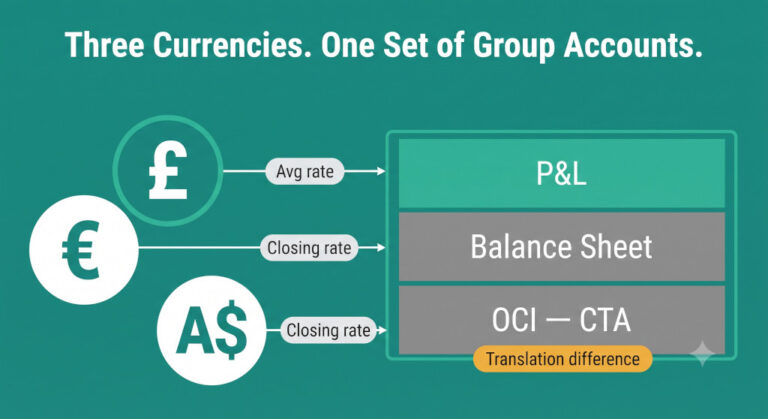
How to Prepare Consolidated Financial Statements for a Group With Multiple Currencies
Yusuf had read the rules. P&L at the average rate. Balance sheet at the closing rate. The difference goes to…
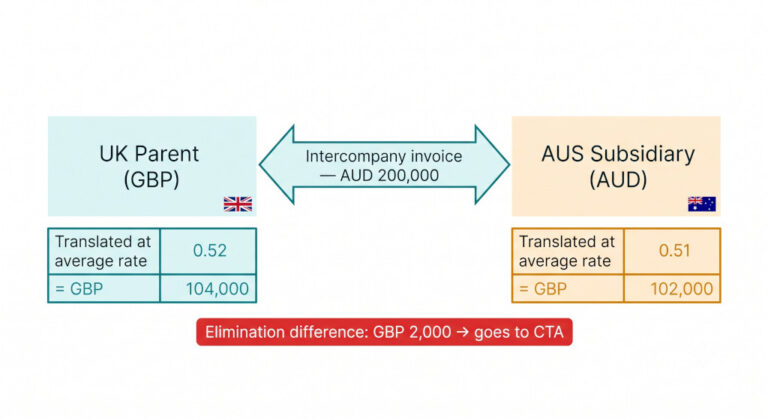
Intercompany Eliminations in Multi-Currency Groups: How Foreign Exchange Affects Your Consolidation Adjustments
The finance director of a UK group with subsidiaries in Australia and Singapore described the problem with characteristic understatement: “The…

Currency Translation Under IAS 21, ASC 830 and FRS 102: What Changes Across Standards
The group had three subsidiaries in three countries, each reporting under a different accounting standard. The UK holding company reported…

Recycling the CTA on Disposal of a Foreign Subsidiary: What Happens to the FCTR When You Sell
The finance director had been preparing the sale of the Singapore subsidiary for six months. She knew the headline figures:…

NCI and Currency Translation Adjustments: How to Split the CTA in Partly-Owned Foreign Subsidiaries
Most finance teams understand the mechanics of currency translation well enough: income statement items are translated at the average rate…

Multi-Entity Accounting Software: Getting CTA Right at Consolidation
Ask any group financial controller which part of the consolidated close they trust least, and the answer is usually the…

How to Calculate the Cumulative Translation Adjustment (CTA) in Group Consolidation
If you have ever prepared or reviewed a consolidated balance sheet and found yourself staring at a line in equity…