currency translation adjustment
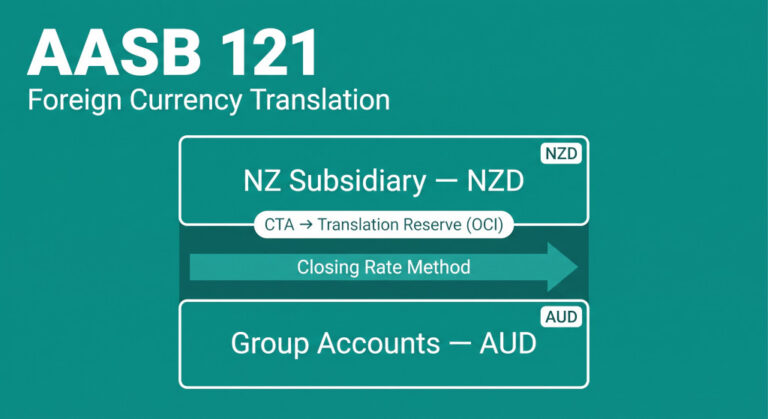
AASB 121 Foreign Currency Translation: A Practical Guide for Australian Multi-Entity Groups
When the auditors reviewed the consolidated accounts of an Australian technology services group, they raised a flag on the New…
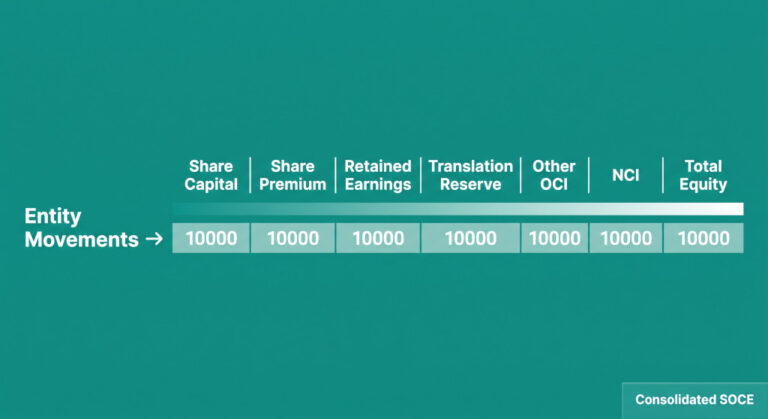
The Consolidated Statement of Changes in Equity: How to Build the Full SOCE From Entity-Level Movements
Priya had been group controller for three years. She had consolidated balance sheets, intercompany eliminations, goodwill calculations, and currency translation…
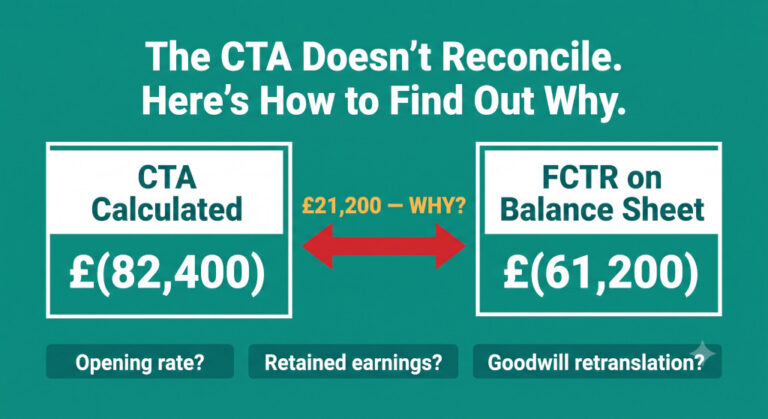
Why Does My CTA Not Reconcile?
Anna had followed the three-rate rule correctly. P&L at the average rate, balance sheet at the closing rate. She had…
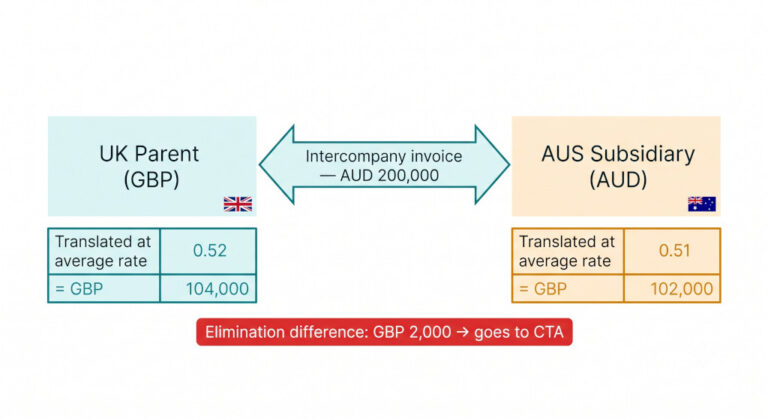
Intercompany Eliminations in Multi-Currency Groups: How Foreign Exchange Affects Your Consolidation Adjustments
The finance director of a UK group with subsidiaries in Australia and Singapore described the problem with characteristic understatement: “The…

Currency Translation Under IAS 21, ASC 830 and FRS 102: What Changes Across Standards
The group had three subsidiaries in three countries, each reporting under a different accounting standard. The UK holding company reported…

NCI in the Consolidated Statement of Changes in Equity: How to Build the NCI Column Correctly
The audit partner had reviewed the consolidated financial statements twice. The income statement looked right. The balance sheet reconciled. But…

Recycling the CTA on Disposal of a Foreign Subsidiary: What Happens to the FCTR When You Sell
The finance director had been preparing the sale of the Singapore subsidiary for six months. She knew the headline figures:…

NCI and Currency Translation Adjustments: How to Split the CTA in Partly-Owned Foreign Subsidiaries
Most finance teams understand the mechanics of currency translation well enough: income statement items are translated at the average rate…

How to Calculate the Cumulative Translation Adjustment (CTA) in Group Consolidation
If you have ever prepared or reviewed a consolidated balance sheet and found yourself staring at a line in equity…