deferred tax
IFRS vs FRS 102: How Goodwill Accounting Differences Force Different Consolidation Adjustments in Mixed-Standard Groups
For SME finance teams managing mixed-standard groups, goodwill is one of the most consequential differences to reconcile at consolidation. FRS…
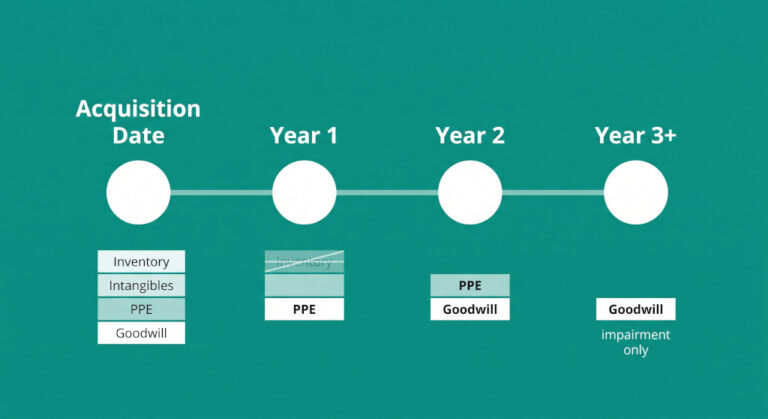
Post-Acquisition Consolidation: The Fair Value Adjustments You Still Need to Make in Year Two — and Every Year After
Priya had been group controller for eight months when she inherited the consolidation working papers for TrainingCo, a subsidiary the…
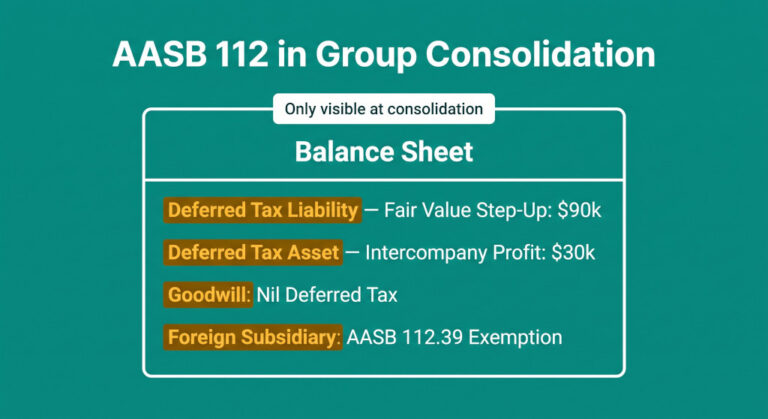
AASB 112 Income Taxes in Group Consolidation: A Practical Guide for Australian Multi-Entity Groups
Chen is the finance director of a Sydney-based manufacturing group with four entities. Three years ago, the group formed a…
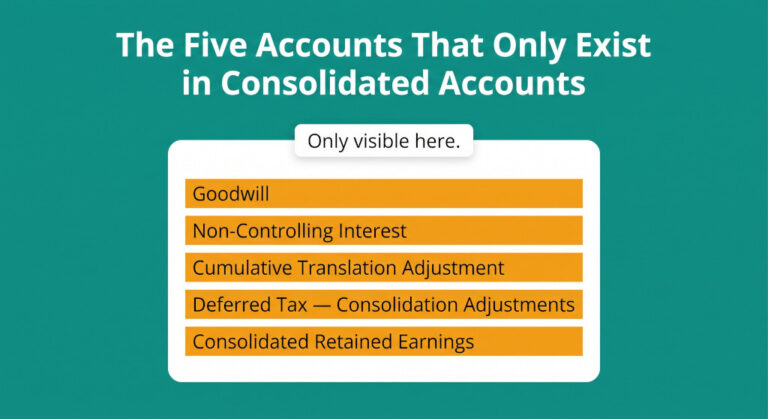
The Five Accounts That Only Exist in Your Consolidated Financial Statements
Tom has just been appointed CFO of an Australian professional services group with four entities. He’s a strong finance leader…
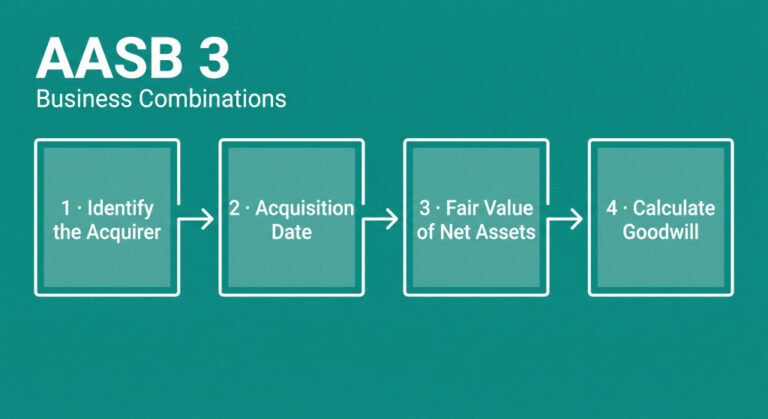
AASB 3 Business Combinations: A Practical Guide for Australian Multi-Entity Groups
When Sophie’s Melbourne-based consulting group acquired a smaller competitor for $2.8 million, the deal took six months of negotiation and…
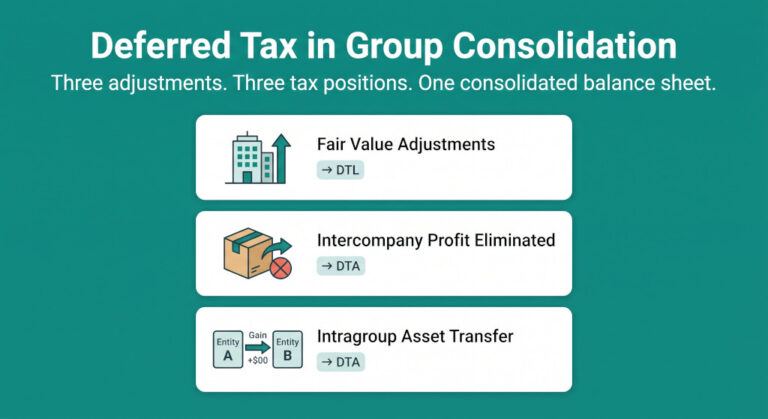
Deferred Tax in Group Consolidation: How Consolidation Adjustments Create Tax Differences
The consolidated deferred tax position is not the sum of the entities’ individual deferred tax balances. Group consolidation introduces adjustments…
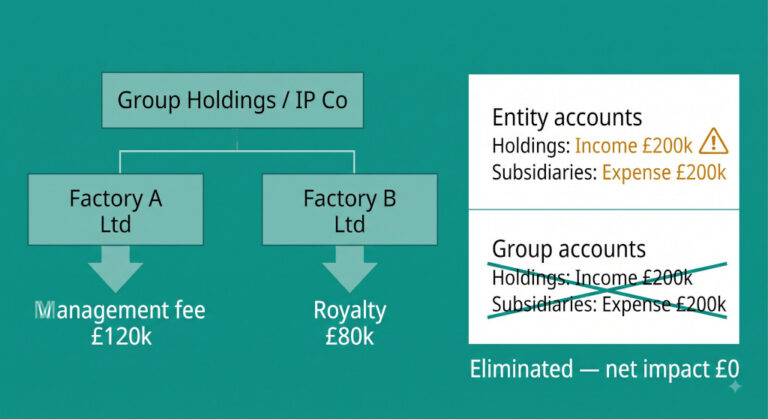
The Revenue That Disappears at Consolidation: Eliminating Management Fees and Royalties in a Manufacturing Group
The group financial controller was reviewing the draft consolidation when she noticed that Group Holdings Ltd was showing £420,000 of…

Acquisition Accounting in Group Consolidation: A Step-by-Step Guide to IFRS 3
When one company acquires another, the transaction creates a set of technical accounting requirements that will affect every group consolidation…