IFRS 16
ASC 842 Leases in Group Consolidation: What US GAAP Multi-Entity Groups Need to Know
When ASC 842 replaced ASC 840, the most headline-grabbing change was straightforward: operating leases, previously kept off balance sheet, now…
IFRS 16 Leases in Group Consolidation: What Multi-Entity Groups Need to Know
When the group finance director sat down to prepare the first IFRS 16 consolidated accounts, she had expected the hardest…
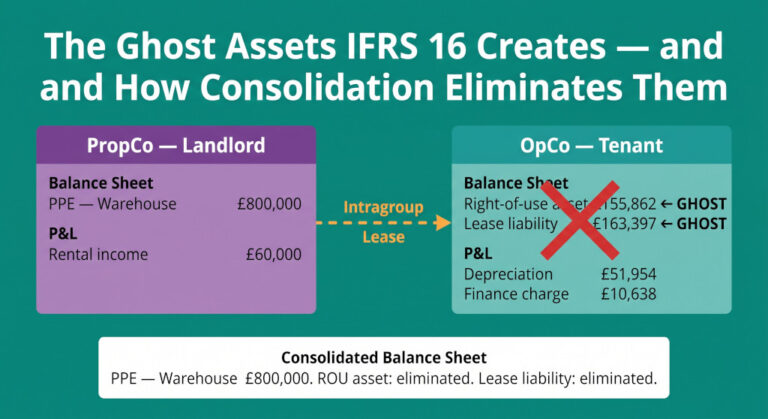
Intragroup Leases in Consolidation: How to Eliminate Ghost IFRS 16 Assets When Landlord and Tenant Are Both in the Group
When one group entity owns a building and leases it to another group entity, something awkward happens at consolidation. The…
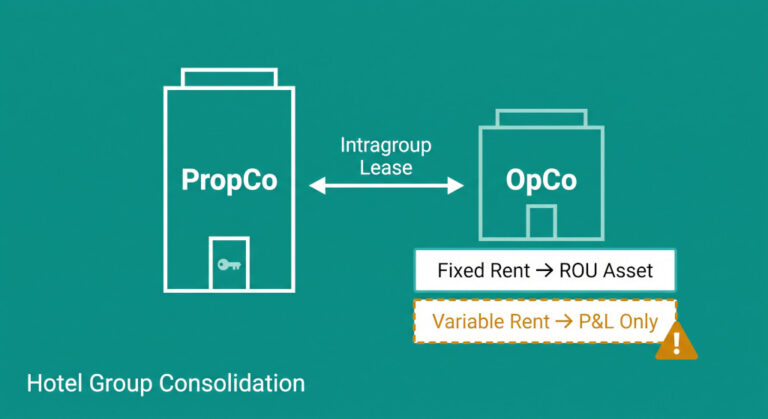
PropCo/OpCo Hotel Leases: The Variable Rent That Doesn’t Appear on the Balance Sheet — and Why Your Consolidation Won’t Balance Without It
Marcus has done everything right. Summit Hotels Group restructured into a PropCo/OpCo arrangement eighteen months ago: Summit PropCo Ltd owns…
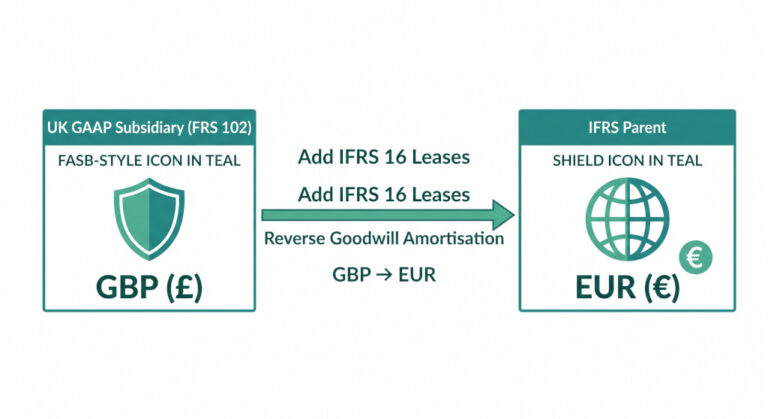
How to Consolidate a UK GAAP (FRS 102) Subsidiary into an IFRS Parent: Lease Recognition, Goodwill Reversal, and GBP Translation
European and international IFRS groups that have acquired UK businesses face a consolidation path that is often underestimated in its…
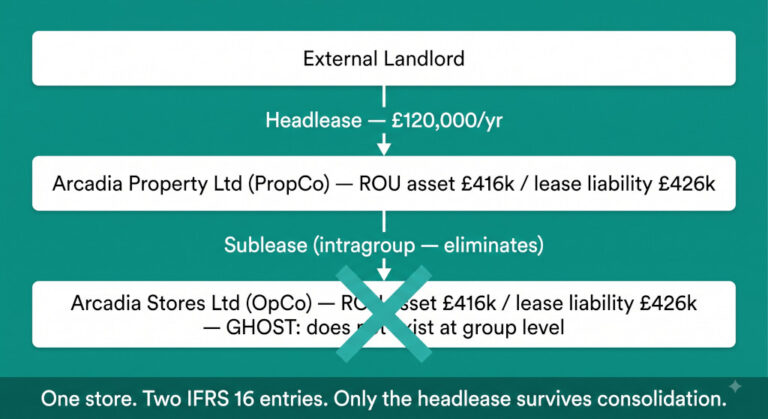
PropCo/OpCo Intragroup Leases in a Retail Group: Eliminating the Ghost IFRS 16 Assets That Shouldn’t Appear on Your Consolidated Balance Sheet
When the group financial controller at Arcadia Retail Group first ran the numbers for the consolidated balance sheet, the total…
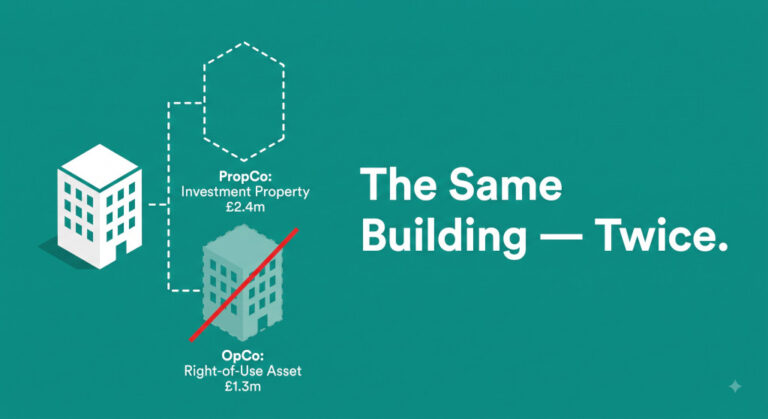
The Same Building, Counted Twice: Eliminating Ghost Assets From Intragroup Leases in Property Groups
Rachel is the group finance director of Meridian Property Holdings, a group that owns eight commercial properties across separate SPV…

IFRS vs UK GAAP: Key Differences in Financial Reporting
Since the UK’s departure from the EU and the decision not to adopt new IFRS standards automatically, the gap between…