Technical Accounting

NCI in the Consolidated Statement of Changes in Equity: How to Build the NCI Column Correctly
The audit partner had reviewed the consolidated financial statements twice. The income statement looked right. The balance sheet reconciled. But…

Recycling the CTA on Disposal of a Foreign Subsidiary: What Happens to the FCTR When You Sell
The finance director had been preparing the sale of the Singapore subsidiary for six months. She knew the headline figures:…

NCI and Currency Translation Adjustments: How to Split the CTA in Partly-Owned Foreign Subsidiaries
Most finance teams understand the mechanics of currency translation well enough: income statement items are translated at the average rate…

Acquisition Accounting in Group Consolidation: A Step-by-Step Guide to IFRS 3
When one company acquires another, the transaction creates a set of technical accounting requirements that will affect every group consolidation…

Goodwill in Group Consolidation: How to Calculate and Account for It in Your Group Accounts
When a group’s holding company acquires a controlling interest in another business, a new figure tends to appear on the…

Equity Method Accounting in Group Consolidation: Associates, Joint Ventures, and Significant Influence
Not every company a group controls or invests in gets fully consolidated. When a parent holds a stake of between…

Multi-Entity Accounting Software: Getting CTA Right at Consolidation
Ask any group financial controller which part of the consolidated close they trust least, and the answer is usually the…

How to Calculate the Cumulative Translation Adjustment (CTA) in Group Consolidation
If you have ever prepared or reviewed a consolidated balance sheet and found yourself staring at a line in equity…
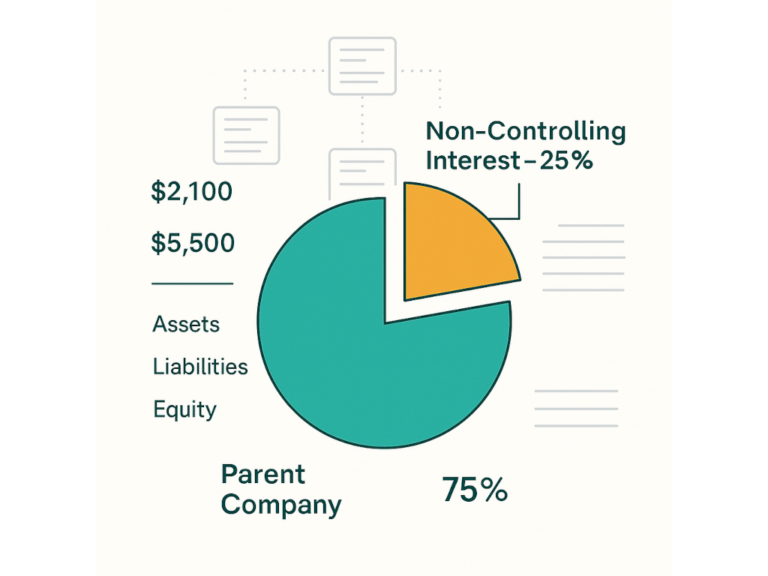
How to Calculate Non-Controlling Interest (NCI) in Financial Consolidation
When a parent company acquires a controlling stake in another business but does not own 100% of it, the financial…