group accounts
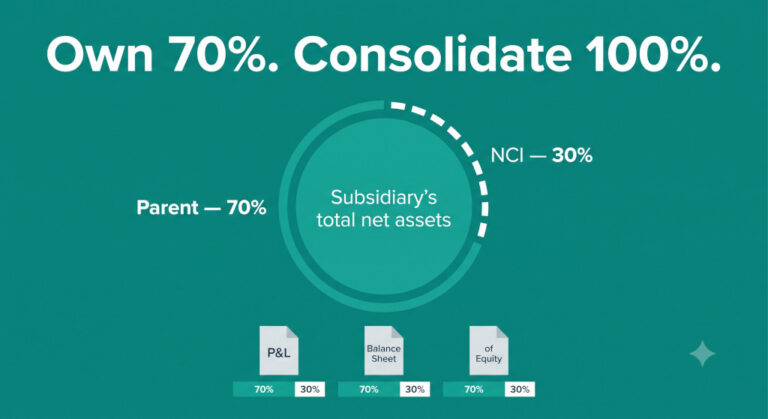
How to Consolidate a Subsidiary When Ownership Is Less Than 100%
For three years, every entity in Daniel’s group was 100% owned. The consolidation was straightforward: add the trial balances together,…
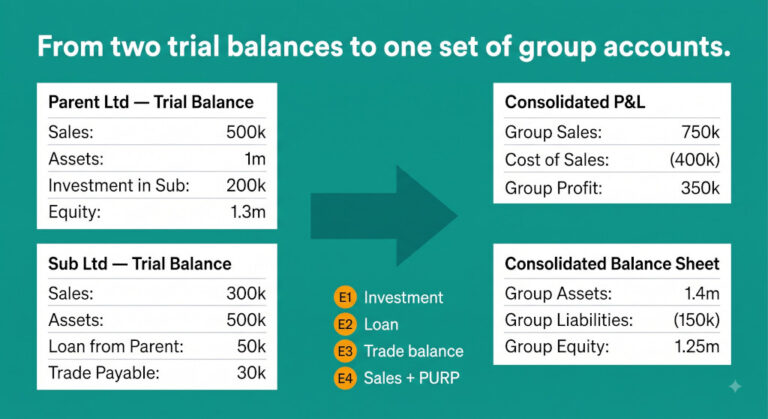
A Complete Consolidation Worked Example: From Entity Trial Balances to Consolidated Financial Statements
Most consolidation guides explain what an intercompany elimination is. Far fewer show you exactly what happens to the numbers when…
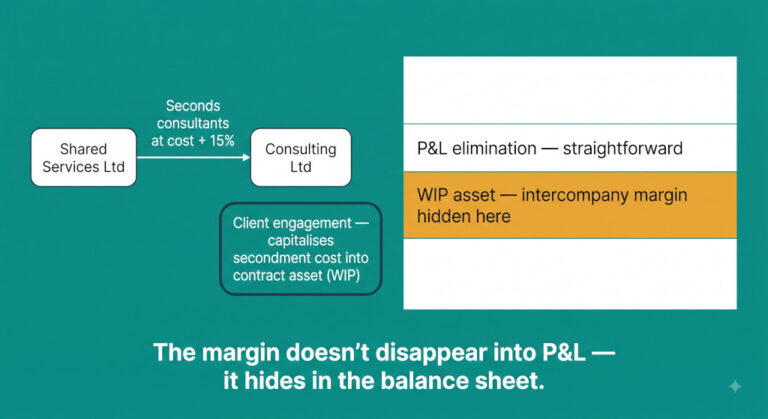
Intercompany Staff Secondments in a Professional Services Group: How the Margin Hides in WIP and What to Do About It
Professional services groups routinely second staff across entities. A shared services centre provides analysts to a client-facing consulting firm. A…
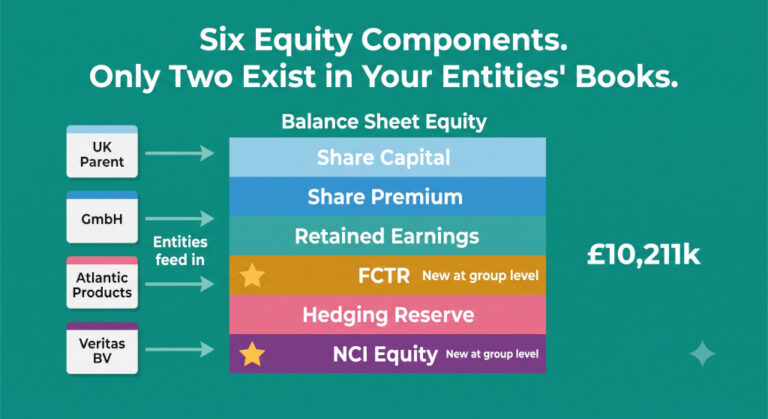
How to Reconcile Consolidated Equity
The audit senior’s email arrived on a Tuesday morning, two weeks before year-end sign-off. Claudia, group financial controller at Veritas…
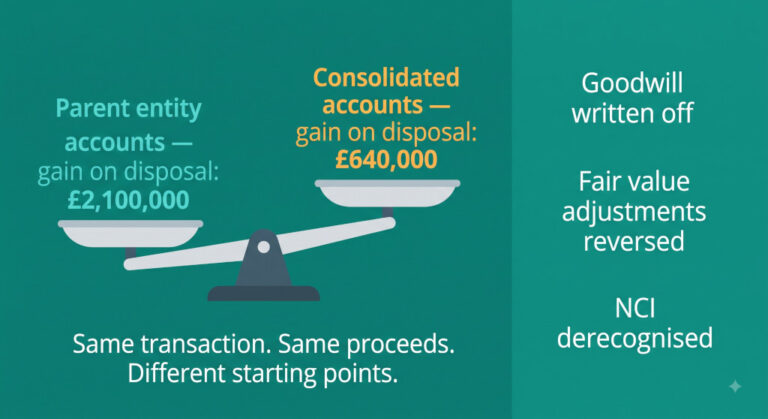
Disposing of a Professional Services Subsidiary: Why the Consolidated Gain and the Entity Gain Are Completely Different Numbers
When a professional services group sells a subsidiary — a regional practice division, a specialist consulting arm, or a standalone…
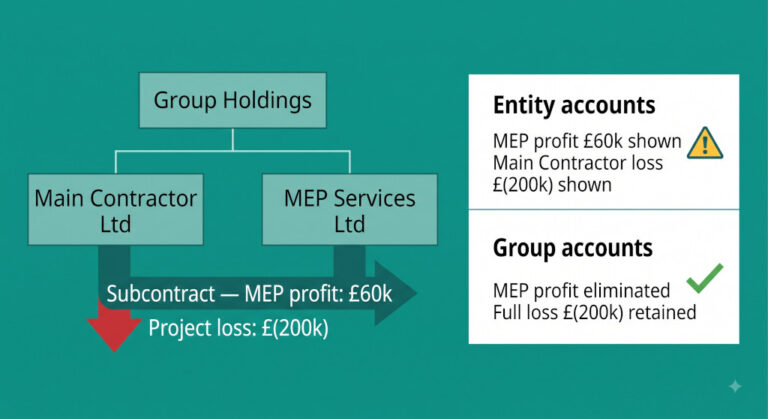
When a Project Goes Wrong: Accounting for Onerous Contracts Across a Construction Group
The group board had known for two quarters that the commercial fit-out contract in Birmingham was in trouble. Materials costs…
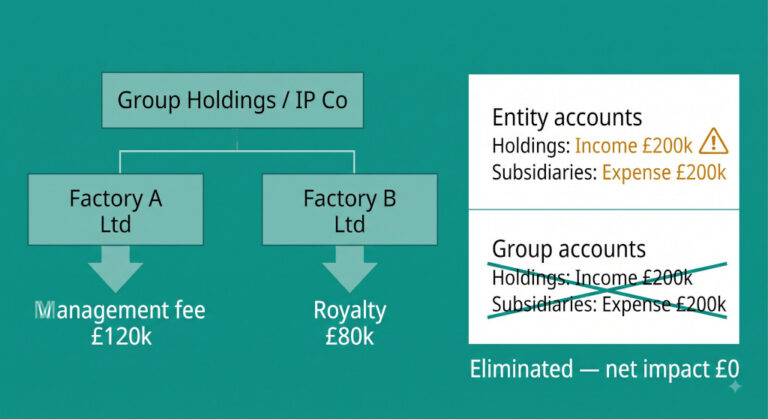
The Revenue That Disappears at Consolidation: Eliminating Management Fees and Royalties in a Manufacturing Group
The group financial controller was reviewing the draft consolidation when she noticed that Group Holdings Ltd was showing £420,000 of…
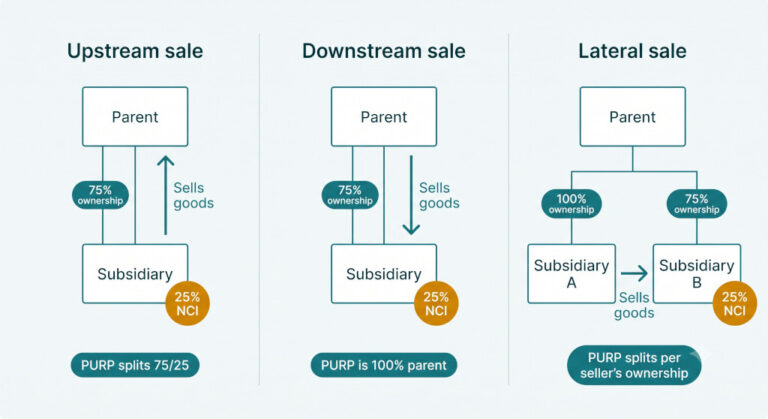
Intercompany Eliminations When There Is a Non-Controlling Interest: Upstream, Downstream, and Lateral Sales
When every subsidiary in a group is wholly owned, intercompany eliminations are mechanically straightforward: the full profit on any intragroup…
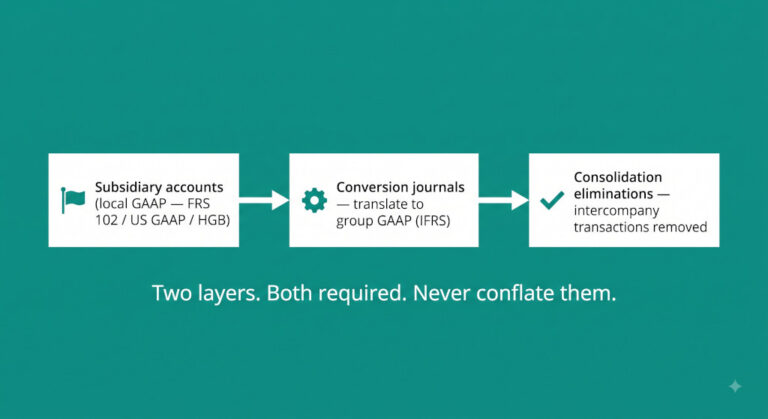
A Practical Cross-GAAP Consolidation Method: Identify Differences, Post Conversion Journals, and Document Review
When every subsidiary in a group uses the same accounting framework as the parent, the consolidation workbook has one layer…
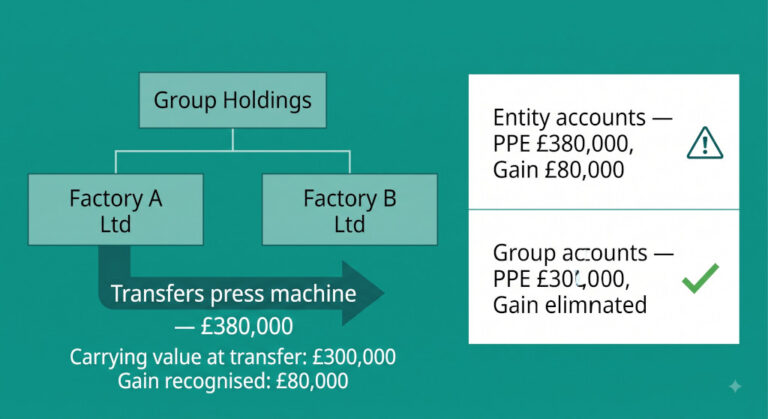
Selling a Machine to Your Own Subsidiary: Why the Disposal Gain Is Fictional and What to Do With It
When a manufacturing group restructures its production capacity, it is common for assets to move between entities. A pressing machine…