IAS 21
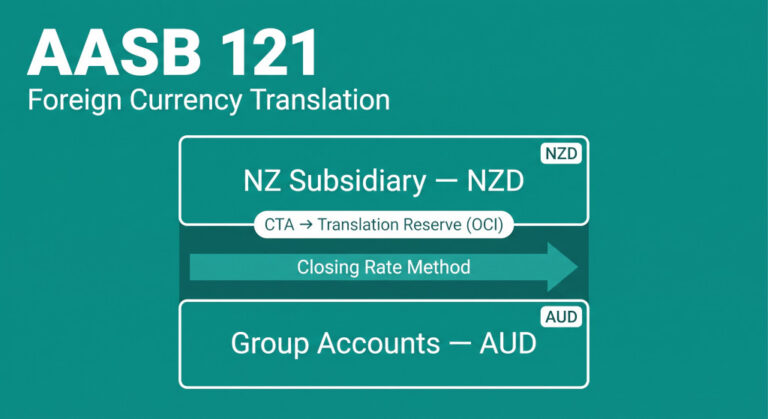
AASB 121 Foreign Currency Translation: A Practical Guide for Australian Multi-Entity Groups
When the auditors reviewed the consolidated accounts of an Australian technology services group, they raised a flag on the New…
IAS 21 Foreign Currency Translation: The IFRS Guide for Multi-Entity Groups
The group’s year-end accounts showed a consolidated loss in other comprehensive income of £2.3 million that nobody in the audit…
US GAAP Foreign Currency Translation: A Practical Guide to ASC 830 for Multi-Entity Groups
The Australian subsidiary had been running profitably for three years. In its own accounts, denominated in Australian dollars, it had…
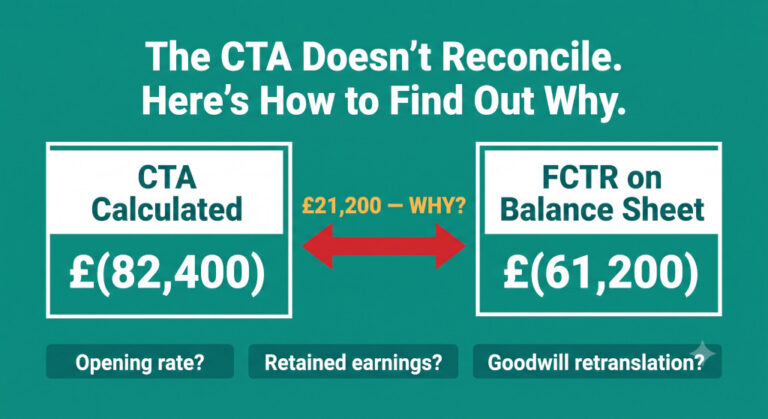
Why Does My CTA Not Reconcile?
Anna had followed the three-rate rule correctly. P&L at the average rate, balance sheet at the closing rate. She had…
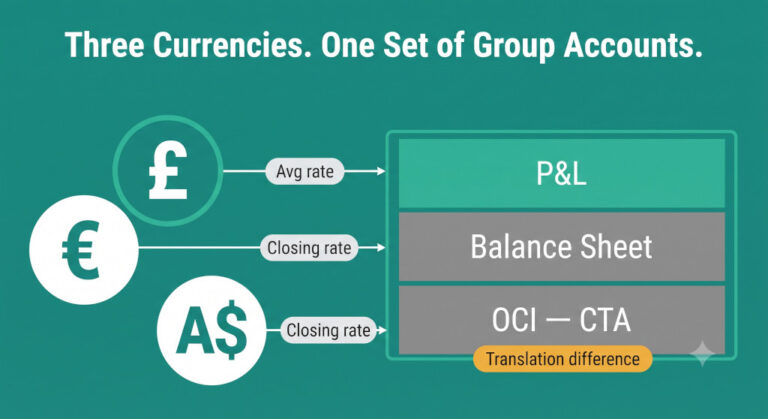
How to Prepare Consolidated Financial Statements for a Group With Multiple Currencies
Yusuf had read the rules. P&L at the average rate. Balance sheet at the closing rate. The difference goes to…
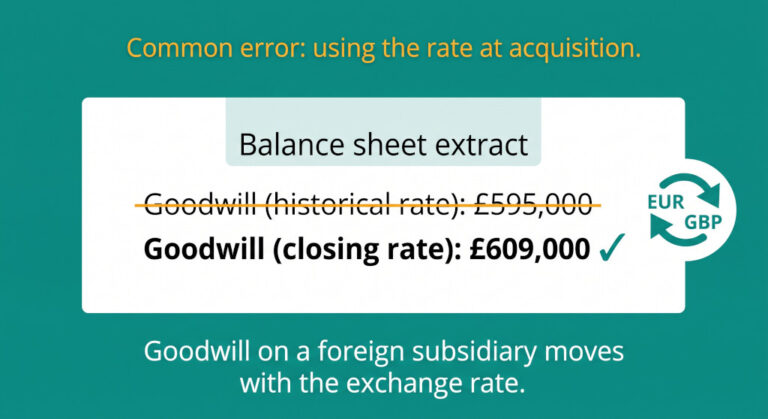
Goodwill on a Foreign Subsidiary: Why It Must Be Retranslated Every Period — and the CTA You Are Probably Not Recording
Rachel is the group financial controller of Nexus Group, a UK-based business that acquired a German subsidiary, Nexus GmbH, eighteen…
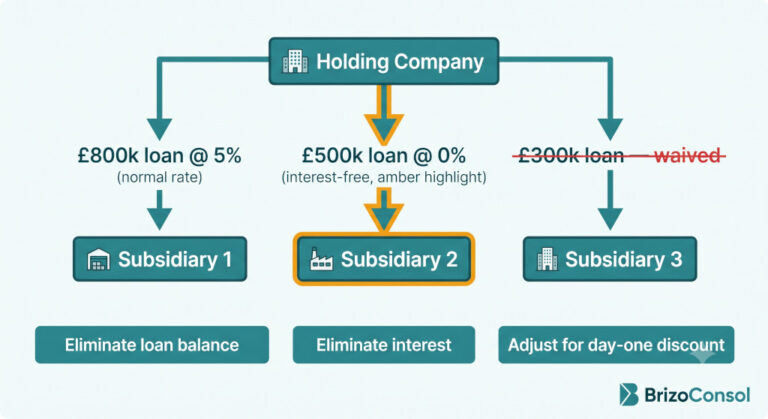
Intercompany Loan Eliminations: A Practical Guide to the Complications That Matter
The basic elimination of an intercompany loan is simple enough: the loan receivable in the parent’s accounts and the loan…
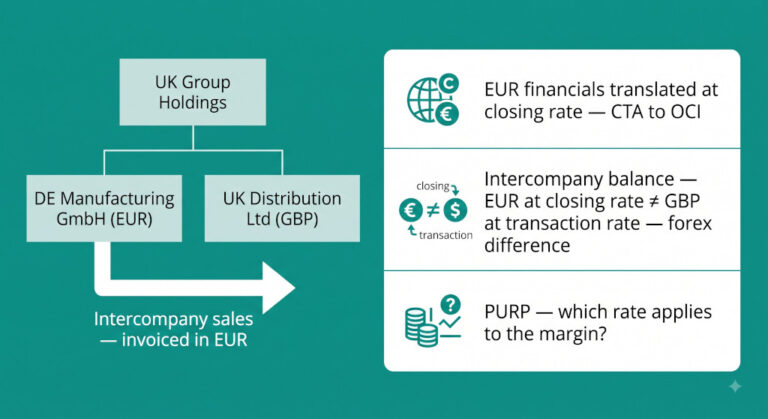
Three Consolidation Problems That Only Exist When Your Factory Is in a Different Currency
The finance director had consolidated the UK group’s two domestic subsidiaries without difficulty every quarter for years. When the board…
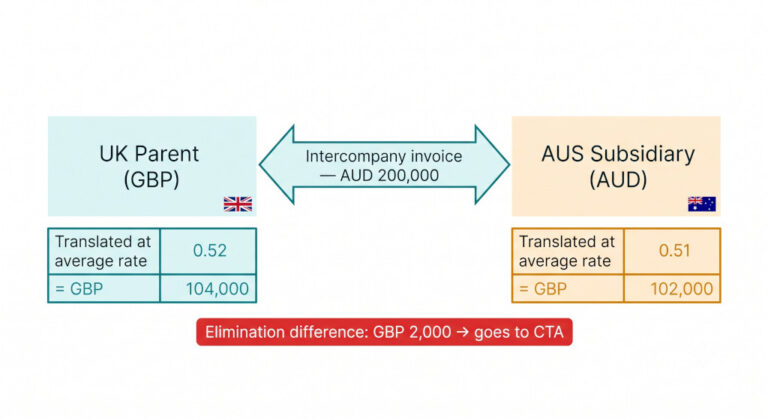
Intercompany Eliminations in Multi-Currency Groups: How Foreign Exchange Affects Your Consolidation Adjustments
The finance director of a UK group with subsidiaries in Australia and Singapore described the problem with characteristic understatement: “The…

Currency Translation Under IAS 21, ASC 830 and FRS 102: What Changes Across Standards
The group had three subsidiaries in three countries, each reporting under a different accounting standard. The UK holding company reported…