IFRS 10
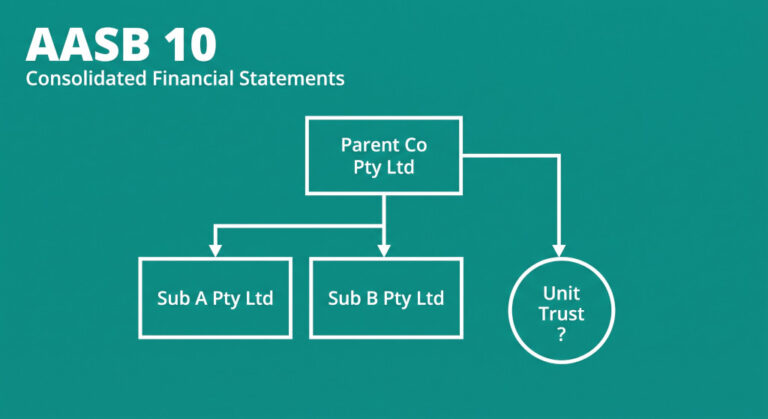
AASB 10 Consolidated Financial Statements: A Practical Guide for Australian Multi-Entity Groups
James had run his family group for fifteen years. What started as a single operations company had grown into six…
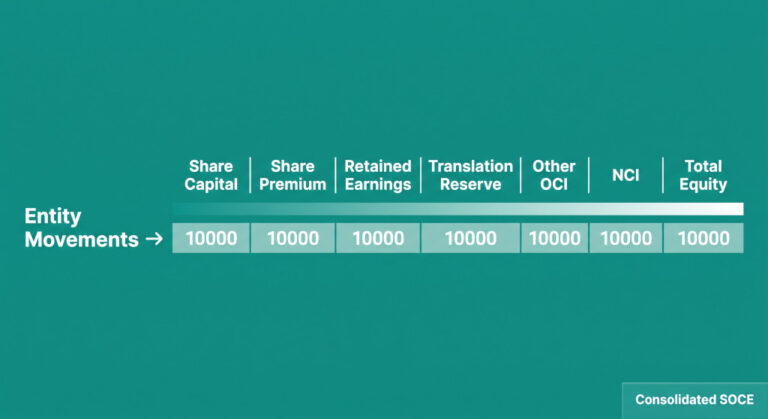
The Consolidated Statement of Changes in Equity: How to Build the Full SOCE From Entity-Level Movements
Priya had been group controller for three years. She had consolidated balance sheets, intercompany eliminations, goodwill calculations, and currency translation…
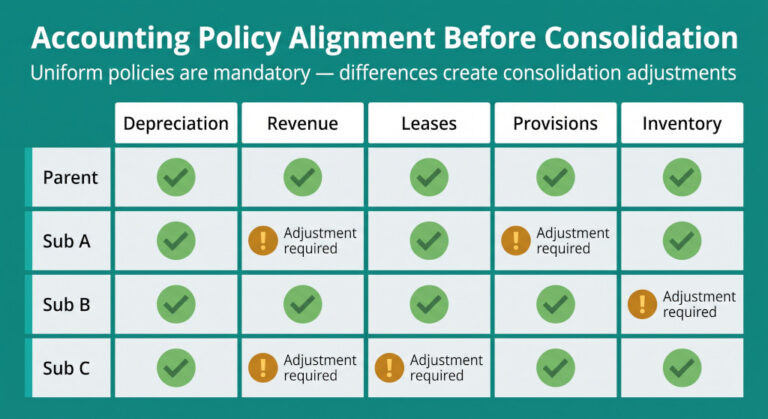
Accounting Policy Alignment Before Consolidation: What to Standardise and How to Document It
A consolidated group is required to prepare its financial statements using uniform accounting policies. IFRS 10 paragraph B87 states this…
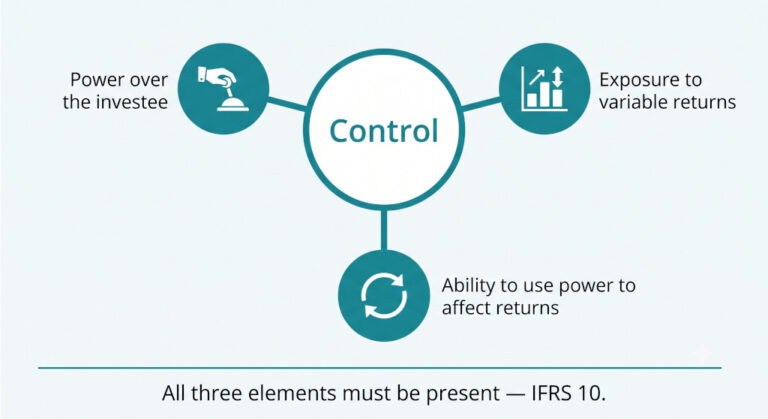
IFRS 10 Consolidated Financial Statements: A Practical Guide for Multi-Entity Groups
When a business owns shares in another company, the first question an accountant must answer is not how to record…
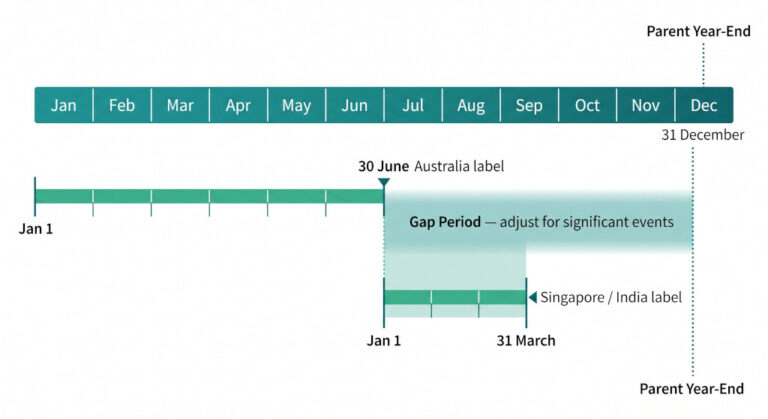
Fiscal Year Alignment in Group Consolidation: Rules, Options, and the Three-Month Rule Explained
One of the less-discussed but practically significant challenges in group consolidation is the fiscal year mismatch. A parent company reporting…
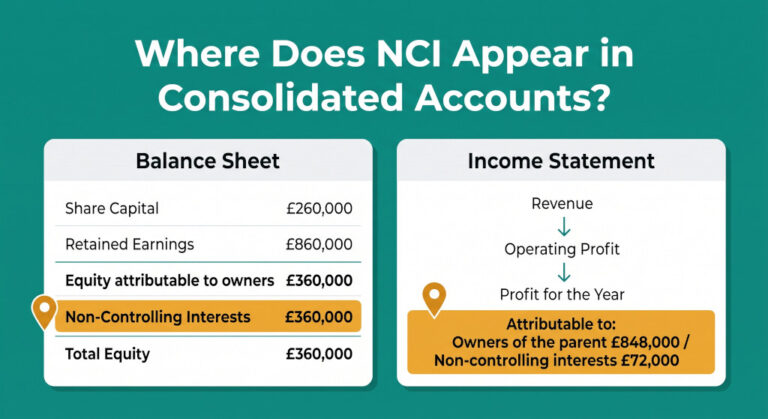
Non-Controlling Interest on the Balance Sheet and Income Statement: Where NCI Appears in Consolidated Financial Statements
Non-controlling interest appears in three places in a set of consolidated financial statements: in the equity section of the balance…
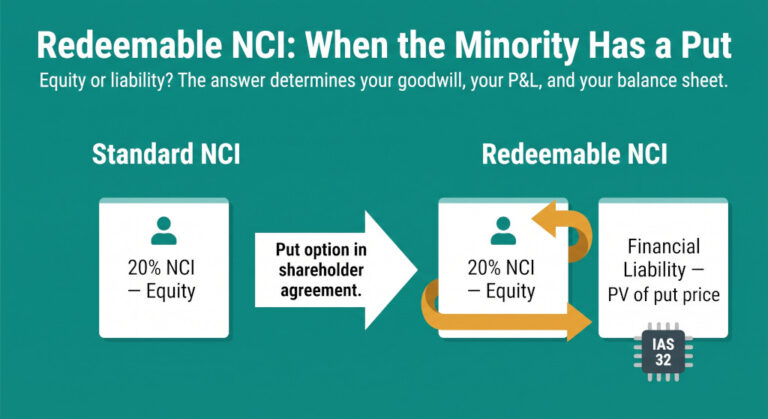
Redeemable NCI: How to Account for Put Options on Non-Controlling Interests
A non-controlling interest does not always sit quietly in equity. When the minority shareholder holds a contractual right to sell…
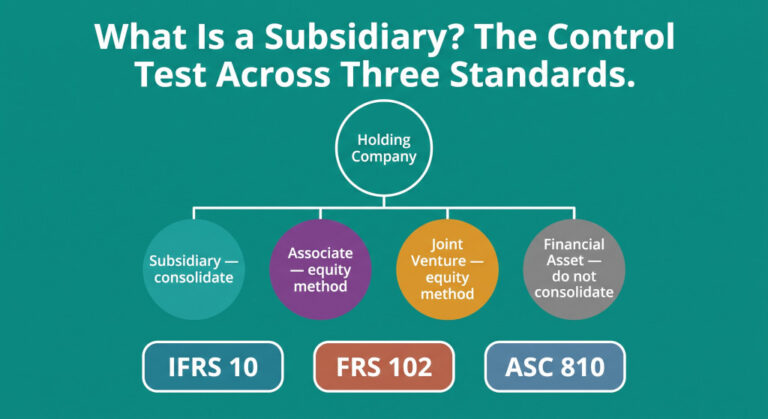
What Is a Subsidiary? How Groups Determine Control Under IFRS 10, FRS 102, and ASC 810
Before a group can begin consolidating, it must know which entities to consolidate. This sounds like a straightforward question —…
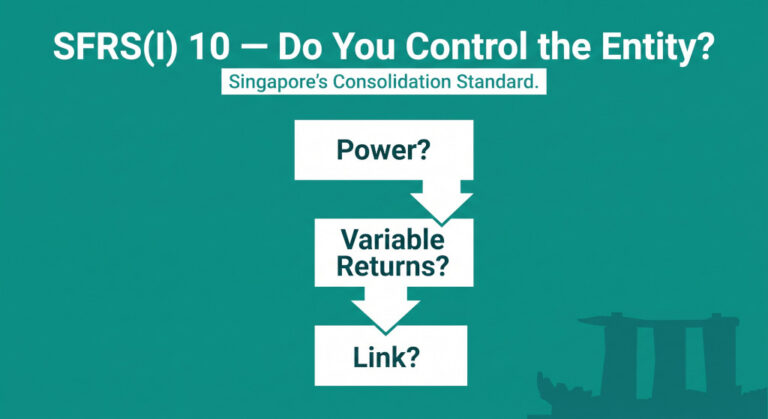
SFRS(I) 10 Consolidated Financial Statements: A Practical Guide for Singapore Groups
When Meridian Capital Group set up its fourth Singapore subsidiary in 2019, the group CFO made an assumption that seemed…
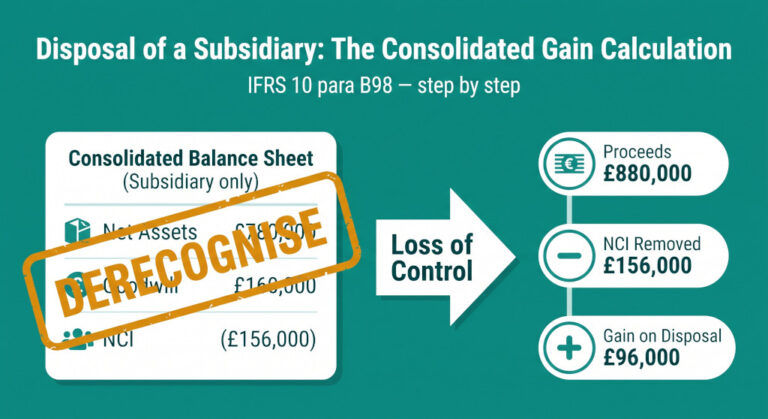
Disposal of a Subsidiary in Group Consolidation: How to Calculate the Gain, Derecognise the Net Assets, and Remove NCI
When a parent loses control of a subsidiary — whether through a full sale, a partial sale that drops below…