IFRS
Goodwill Allocated to a Cash-Generating Unit That Includes a Foreign Subsidiary: How to Retranslate, Test, and Record the Impairment at Consolidation
When a group acquires a foreign subsidiary, goodwill must be retranslated at every closing rate, tested for impairment in the…
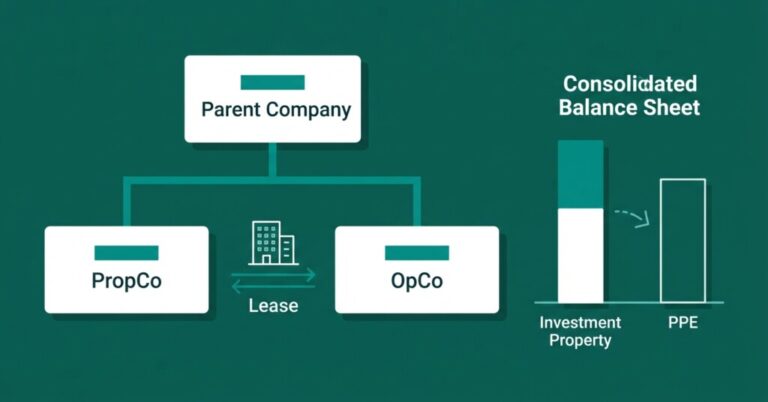
IFRS vs FRS 102: How Investment Property Accounting Differences Force Different Consolidation Adjustments When a UK Subsidiary Holds Group Real Estate
When a UK subsidiary holds property leased to another group entity, the accounting standard it applies — FRS 102 or…
Transfer Pricing for Intercompany Component Sales in a Manufacturing Group: How to Set Arm’s-Length Prices and Eliminate the Margin at Consolidation
When one entity in your manufacturing group sells components to a sister company, the transfer price shapes both your tax…
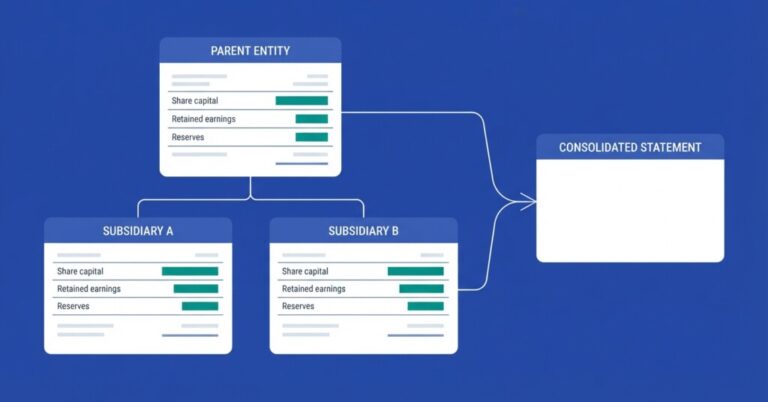
Why Xero’s Report Templates Can’t Produce a Consolidated Statement of Changes in Equity Across Multiple Organisations
Xero's report templates are built for single-entity reporting and cannot produce a consolidated Statement of Changes in Equity across multiple…
IFRS vs FRS 102: How Goodwill Accounting Differences Force Different Consolidation Adjustments in Mixed-Standard Groups
For SME finance teams managing mixed-standard groups, goodwill is one of the most consequential differences to reconcile at consolidation. FRS…
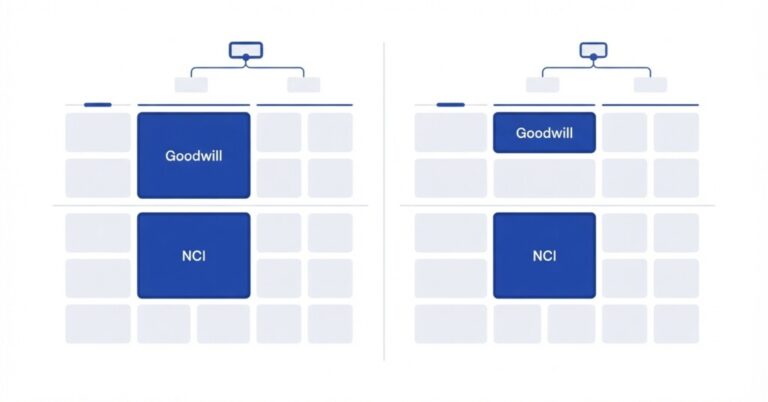
IFRS vs US GAAP: How NCI Measurement Differences Change Your Consolidated Balance Sheet
IFRS and US GAAP treat non-controlling interest measurement differently at acquisition date, and those differences compound across goodwill calculations, equity…
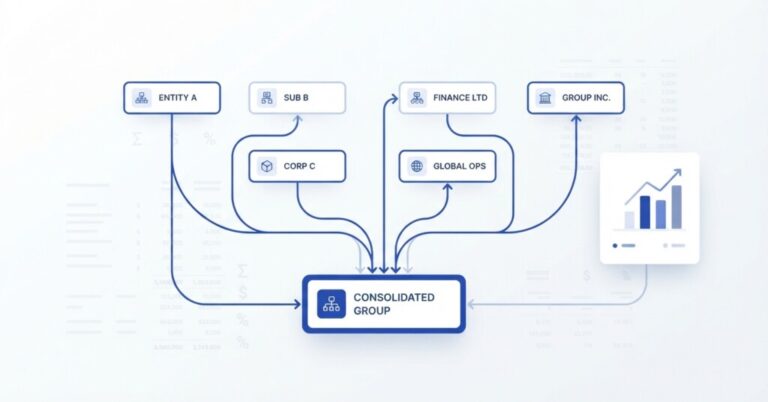
IFRS vs AASB: Key Differences That Affect Multi-Entity Group Consolidation in Australia
IFRS and AASB standards are closely aligned, but the differences that exist carry real consequences for multi-entity consolidation in Australia.…
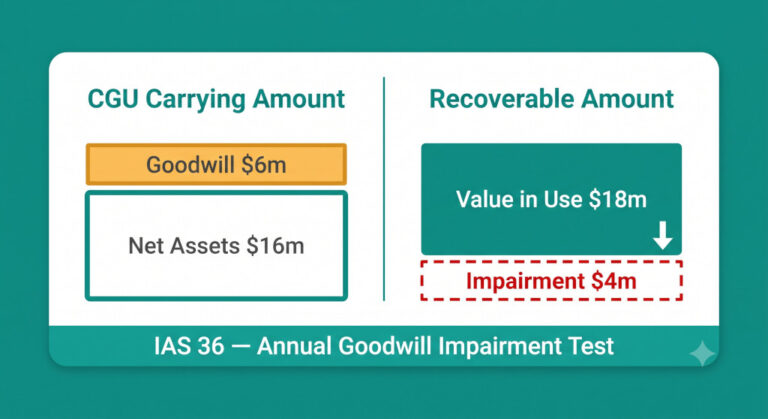
IAS 36 Goodwill Impairment Testing: A Practical Guide for IFRS Multi-Entity Groups
When a UK-based manufacturing group acquired a German competitor in 2019, the purchase price allocation under IFRS 3 left €14…
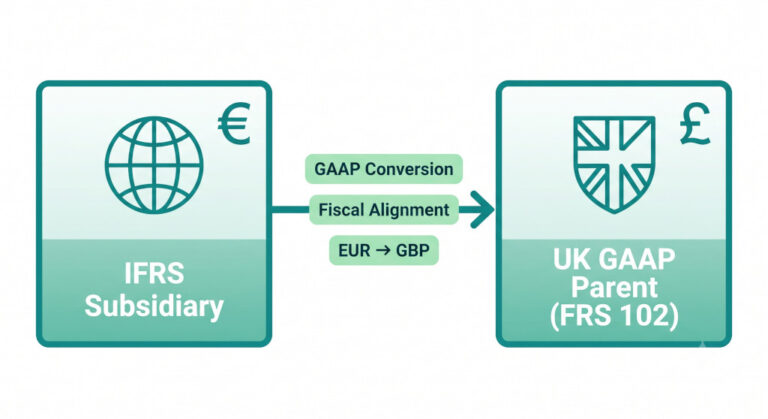
How to Consolidate an IFRS Subsidiary into a UK GAAP (FRS 102) Parent: Journals, Fiscal Periods, and Currency Translation
UK groups that have grown through acquisition — particularly those with European or international subsidiaries — often find themselves in…
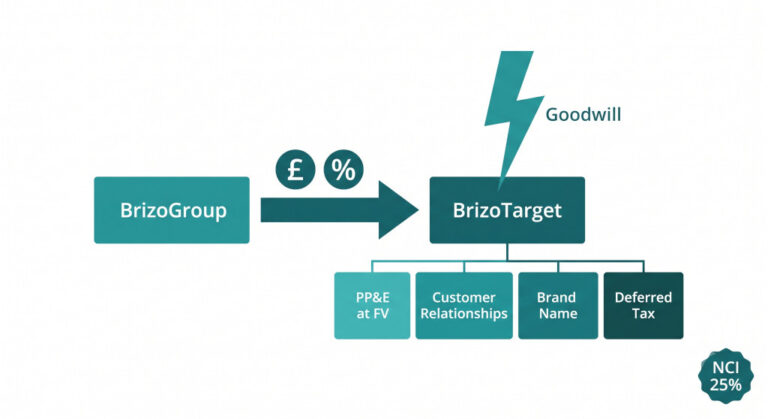
IFRS 3 Business Combinations: A Practical Guide for Multi-Entity Groups
Every consolidation begins with an acquisition. And every acquisition governed by IFRS starts with IFRS 3 Business Combinations — the standard that…