FRS 102
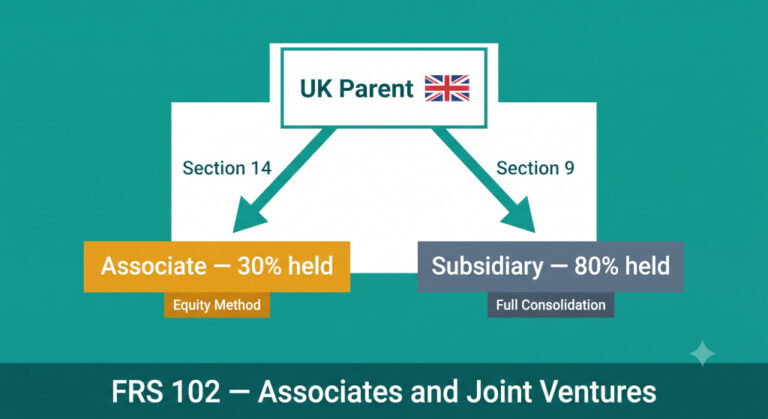
FRS 102 Associates and Joint Ventures: The Equity Method for UK Multi-Entity Groups
A UK manufacturing group held a 35% stake in a specialist components supplier for eleven years, accounting for its share…
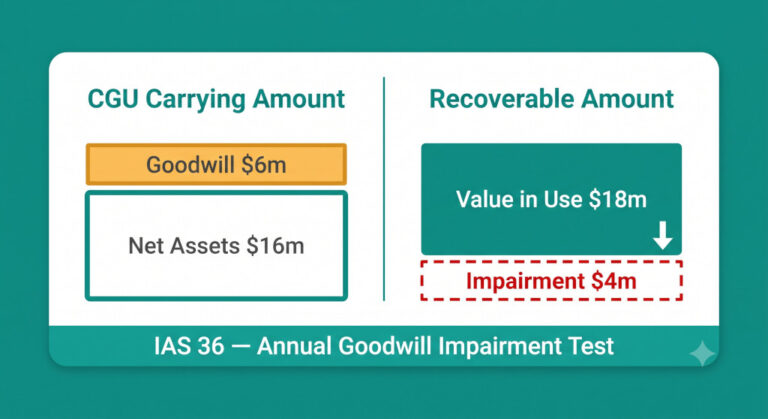
IAS 36 Goodwill Impairment Testing: A Practical Guide for IFRS Multi-Entity Groups
When a UK-based manufacturing group acquired a German competitor in 2019, the purchase price allocation under IFRS 3 left €14…
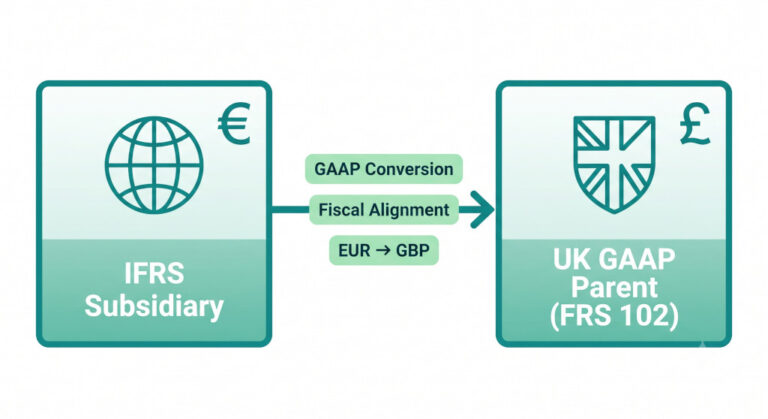
How to Consolidate an IFRS Subsidiary into a UK GAAP (FRS 102) Parent: Journals, Fiscal Periods, and Currency Translation
UK groups that have grown through acquisition — particularly those with European or international subsidiaries — often find themselves in…
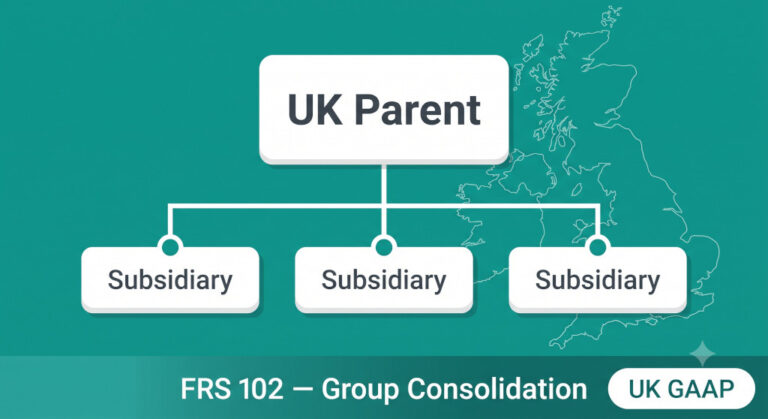
FRS 102 Consolidation: A Practical Guide for UK Multi-Entity Groups
The holding company had been incorporated two years earlier to sit above three trading subsidiaries, and the group’s accountants had…
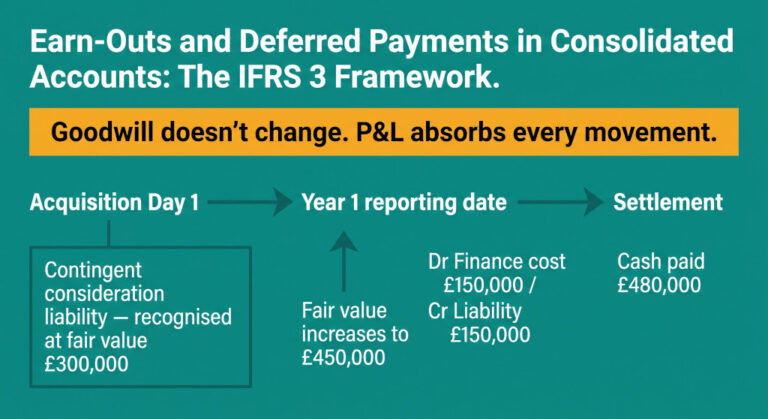
Contingent Consideration in Group Consolidation: Why Earn-Outs and Deferred Payments Look Different in Your Consolidated Accounts
When a group acquires a business, the consideration paid is rarely a single clean cash figure. Most acquisitions include some…
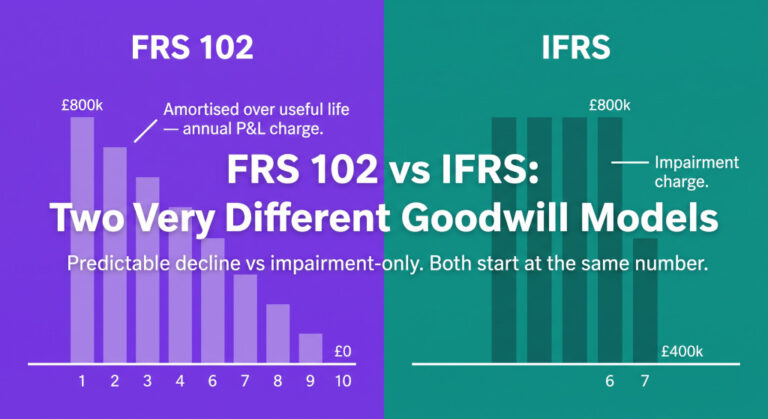
FRS 102 Goodwill Amortisation: How UK GAAP Groups Account for Goodwill Differently From IFRS
Goodwill is one of the most significant balance sheet items in any acquisitive group, and the accounting treatment depends entirely…
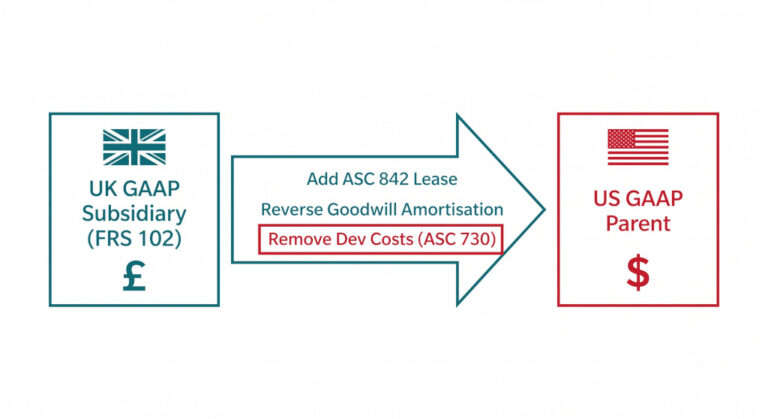
How to Consolidate a UK GAAP (FRS 102) Subsidiary into a US GAAP Parent: Leases, Goodwill, and the Development Cost Reversal
US-listed and SEC-reporting companies that own UK businesses face a consolidation path with a distinctive wrinkle absent from every other…
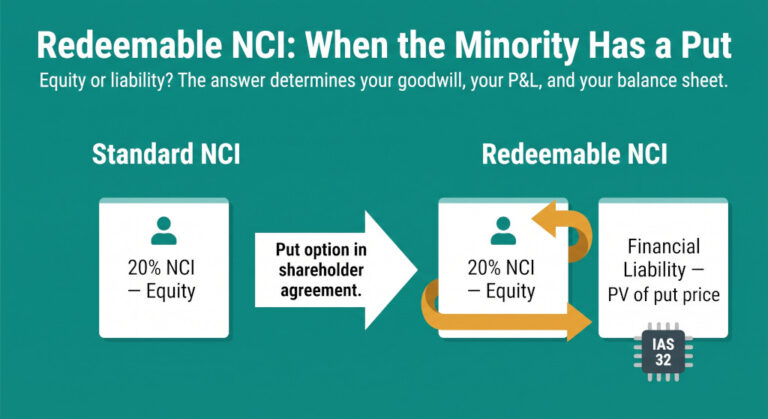
Redeemable NCI: How to Account for Put Options on Non-Controlling Interests
A non-controlling interest does not always sit quietly in equity. When the minority shareholder holds a contractual right to sell…
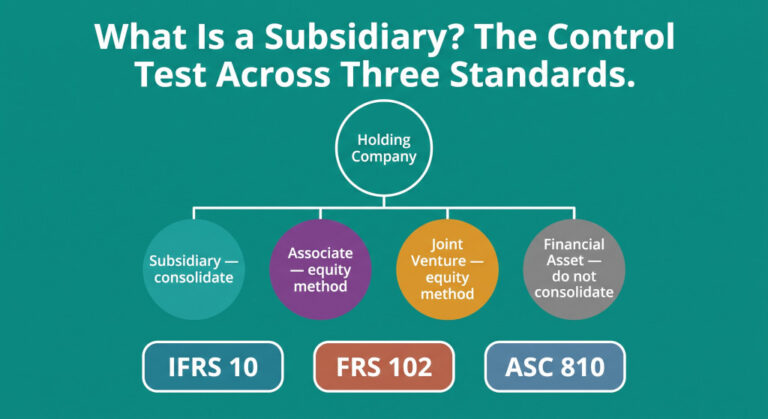
What Is a Subsidiary? How Groups Determine Control Under IFRS 10, FRS 102, and ASC 810
Before a group can begin consolidating, it must know which entities to consolidate. This sounds like a straightforward question —…
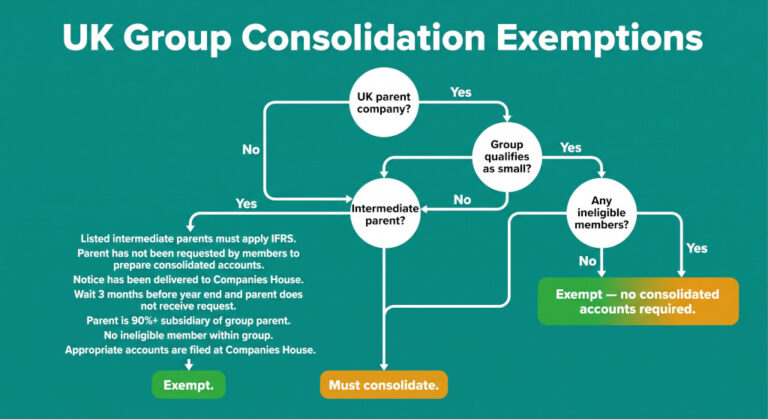
UK Group Consolidation Exemptions: When a UK Group Is Not Required to Prepare Consolidated Accounts
The conversation happened in the third week of March. Sarah, group financial controller at a mid-sized professional services group with…