FRS 102
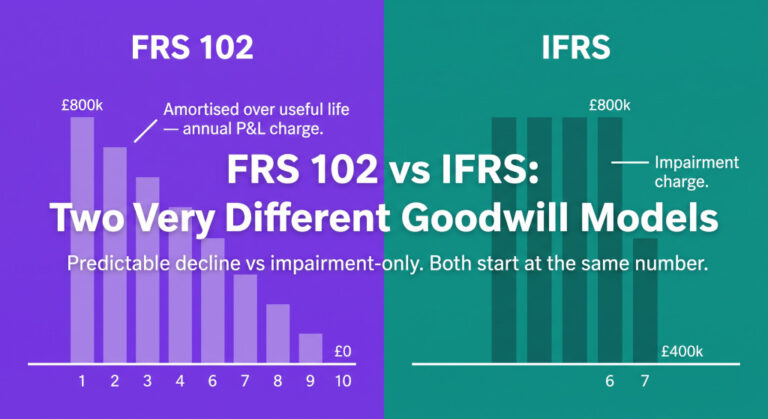
FRS 102 Goodwill Amortisation: How UK GAAP Groups Account for Goodwill Differently From IFRS
Goodwill is one of the most significant balance sheet items in any acquisitive group, and the accounting treatment depends entirely…
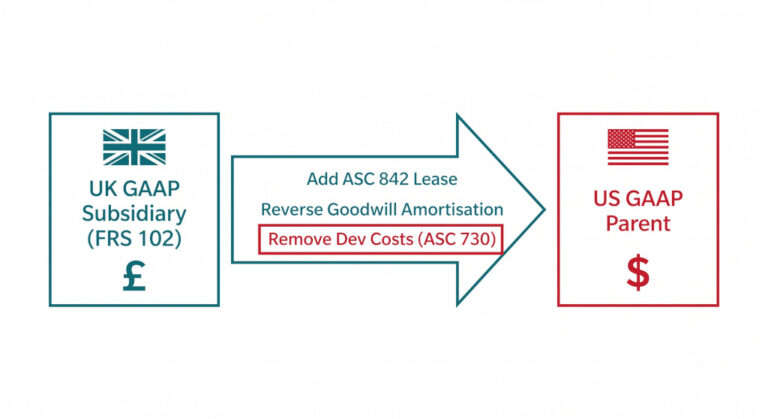
How to Consolidate a UK GAAP (FRS 102) Subsidiary into a US GAAP Parent: Leases, Goodwill, and the Development Cost Reversal
US-listed and SEC-reporting companies that own UK businesses face a consolidation path with a distinctive wrinkle absent from every other…
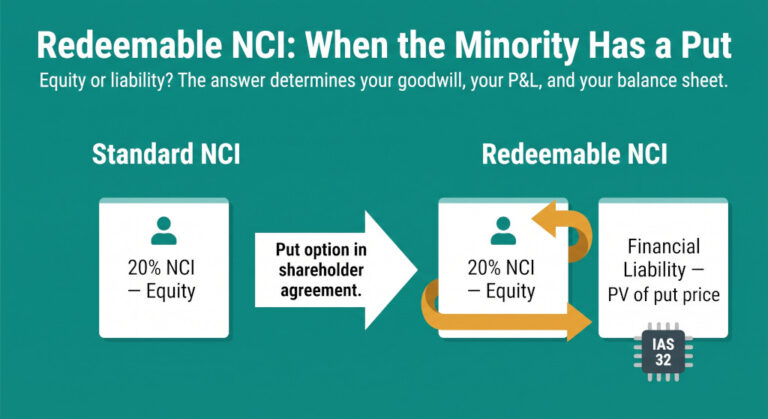
Redeemable NCI: How to Account for Put Options on Non-Controlling Interests
A non-controlling interest does not always sit quietly in equity. When the minority shareholder holds a contractual right to sell…
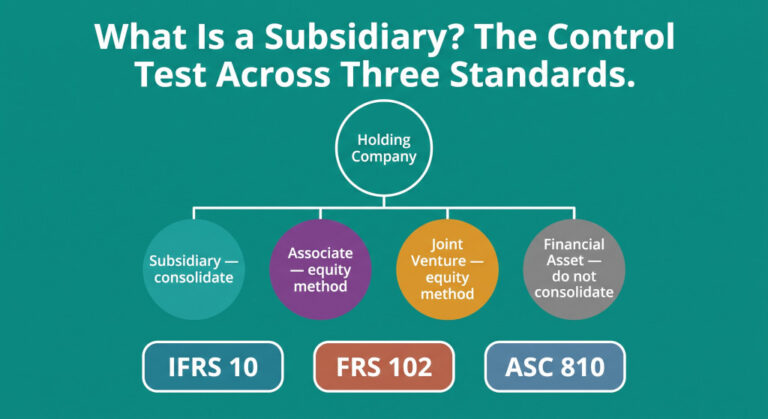
What Is a Subsidiary? How Groups Determine Control Under IFRS 10, FRS 102, and ASC 810
Before a group can begin consolidating, it must know which entities to consolidate. This sounds like a straightforward question —…
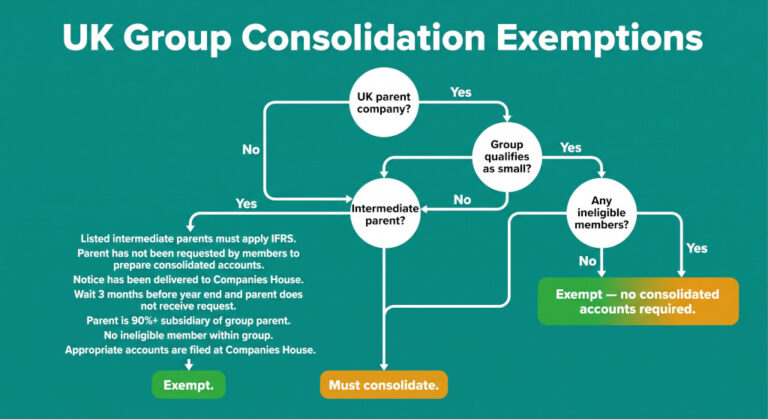
UK Group Consolidation Exemptions: When a UK Group Is Not Required to Prepare Consolidated Accounts
The conversation happened in the third week of March. Sarah, group financial controller at a mid-sized professional services group with…
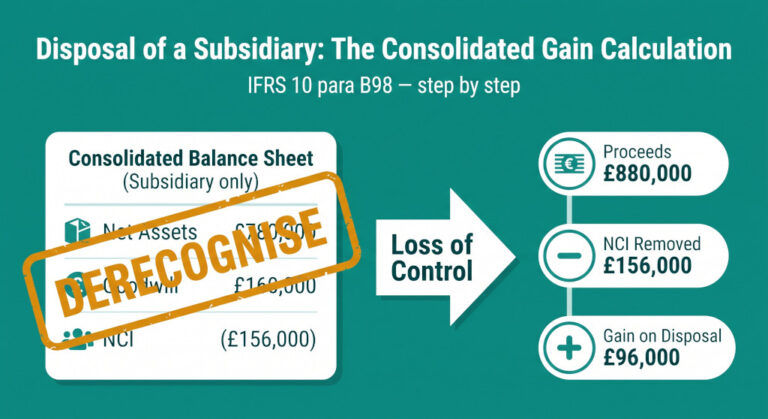
Disposal of a Subsidiary in Group Consolidation: How to Calculate the Gain, Derecognise the Net Assets, and Remove NCI
When a parent loses control of a subsidiary — whether through a full sale, a partial sale that drops below…
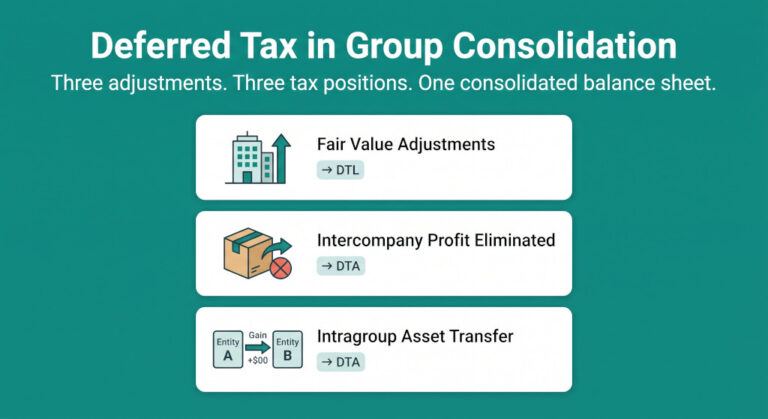
Deferred Tax in Group Consolidation: How Consolidation Adjustments Create Tax Differences
The consolidated deferred tax position is not the sum of the entities’ individual deferred tax balances. Group consolidation introduces adjustments…
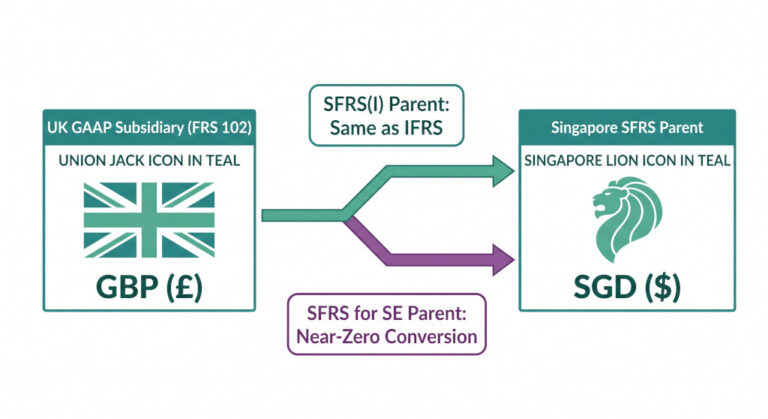
How to Consolidate a UK GAAP (FRS 102) Subsidiary into an SFRS Parent: Two Very Different Conversion Paths
Singapore holding companies that own UK operating businesses face a consolidation question that looks deceptively straightforward: how different is FRS…
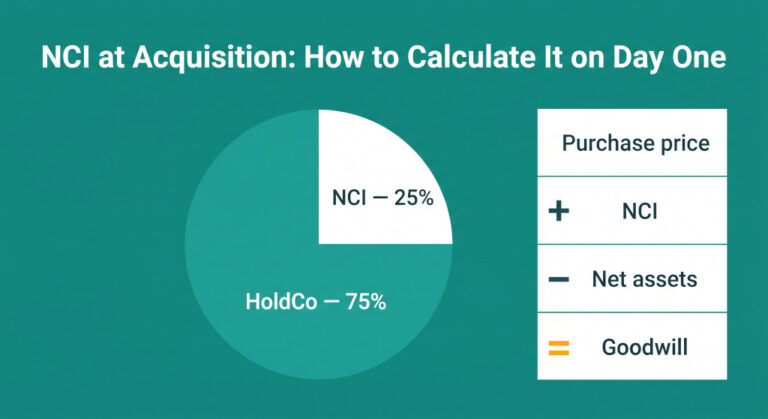
NCI at Acquisition: How to Calculate Non-Controlling Interest on the Date of Purchase
When HoldCo acquires 75% of SubCo, it controls SubCo from the acquisition date and must consolidate SubCo’s full balance sheet…
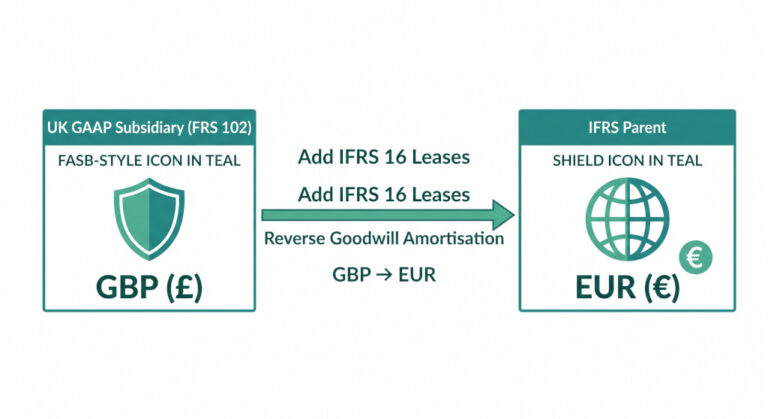
How to Consolidate a UK GAAP (FRS 102) Subsidiary into an IFRS Parent: Lease Recognition, Goodwill Reversal, and GBP Translation
European and international IFRS groups that have acquired UK businesses face a consolidation path that is often underestimated in its…