NCI
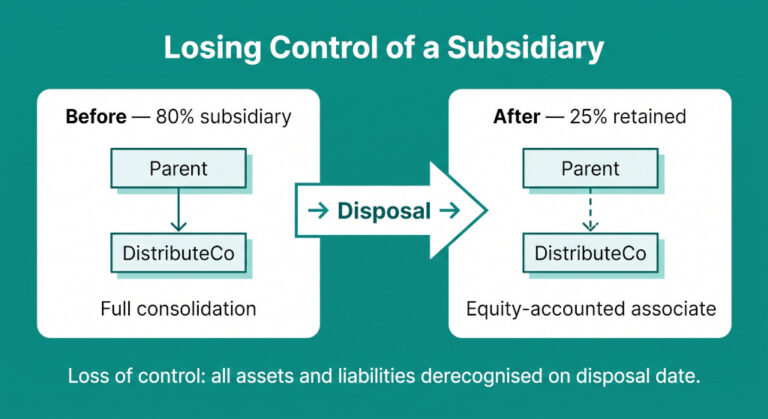
Losing Control of a Subsidiary: The Consolidation Accounting for Disposal Under IFRS 10
The group had owned 80% of DistributeCo for six years. DistributeCo’s revenue appeared in the consolidated income statement. Its assets…
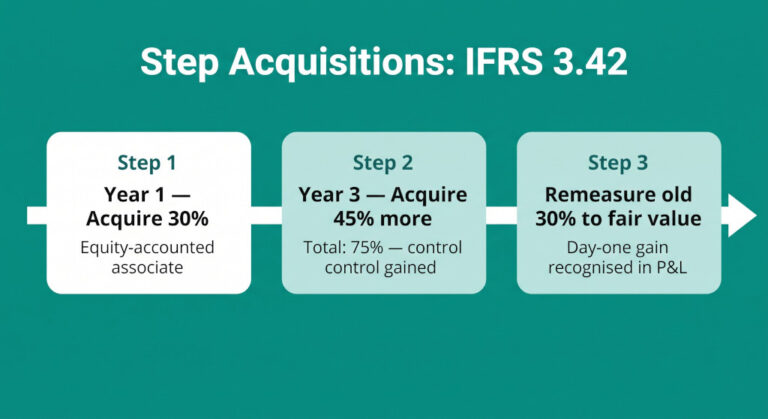
Gaining Control in Stages: How to Account for a Step Acquisition Under IFRS 3
Three years ago, the group took a 30% stake in TechCo, a software business with strong growth potential. The investment…
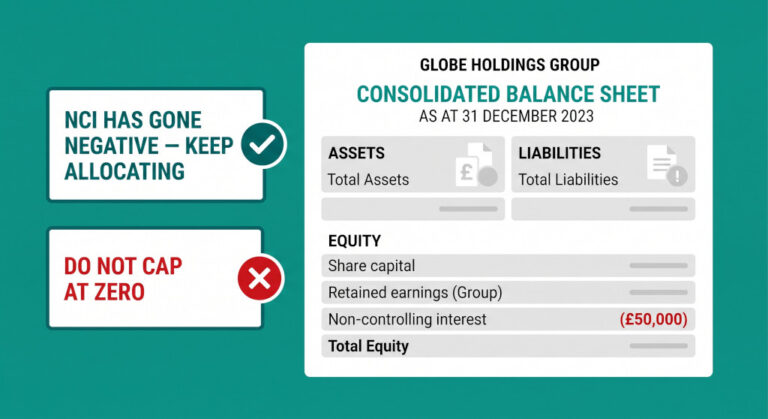
When a Partly-Owned Subsidiary Has Accumulated Losses That Exceed Its Equity: How to Handle Negative NCI at Consolidation
Marcus had been finance director at the wellness group for two years when his management accountant flagged something unusual in…
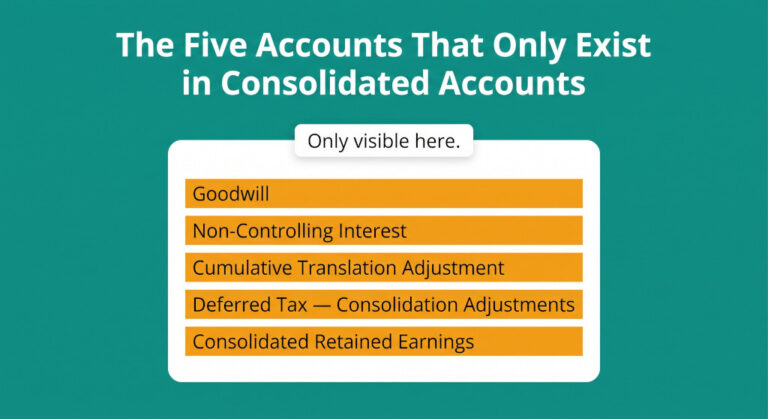
The Five Accounts That Only Exist in Your Consolidated Financial Statements
Tom has just been appointed CFO of an Australian professional services group with four entities. He’s a strong finance leader…
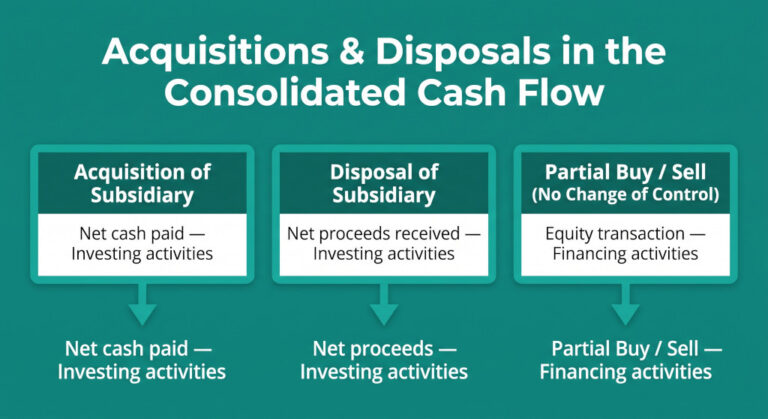
Acquisitions and Disposals in the Consolidated Cash Flow Statement
Daniel’s group had a busy year. In March, it acquired a software business for $3.2 million — $2.5 million paid…
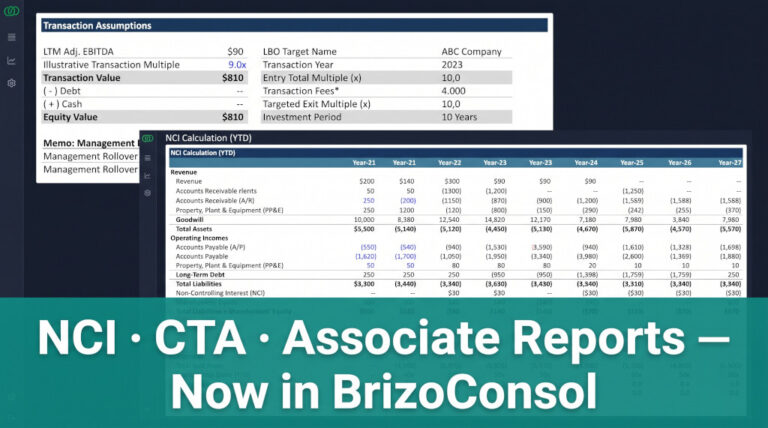
NCI, CTA, and JV/Associate Reports: Audit-Ready Consolidation Workings Now Built Into BrizoConsol
Audit season for group accounts has a predictable shape. The auditors ask for the consolidation workpapers. The group controller produces…
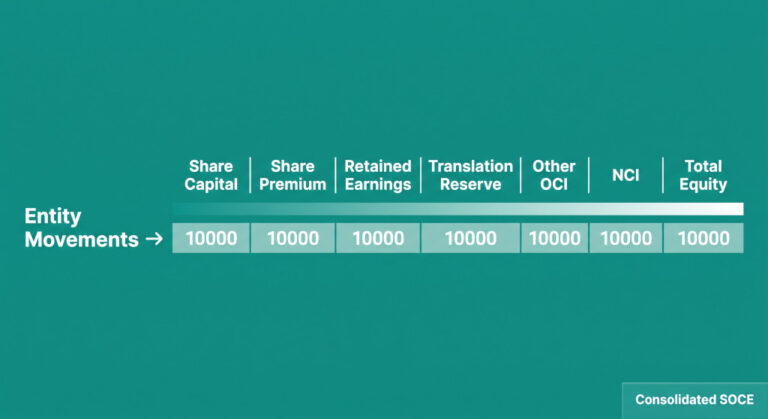
The Consolidated Statement of Changes in Equity: How to Build the Full SOCE From Entity-Level Movements
Priya had been group controller for three years. She had consolidated balance sheets, intercompany eliminations, goodwill calculations, and currency translation…
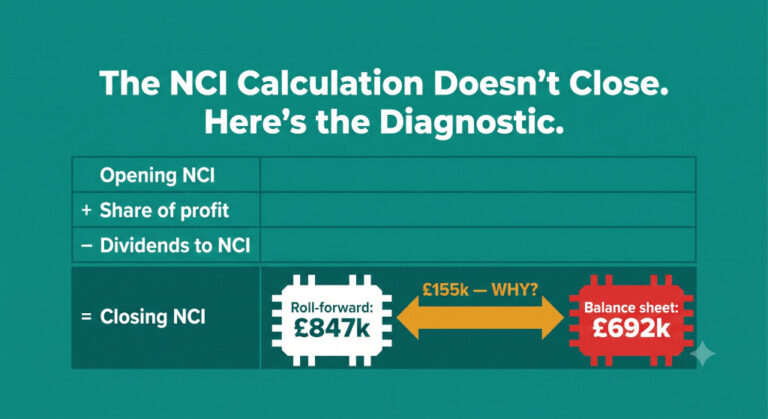
Why Does My NCI Calculation Not Match?
Owen had two partially-owned subsidiaries in his group. Harrow Manufacturing Ltd (60% group ownership, 40% NCI) had been in the…
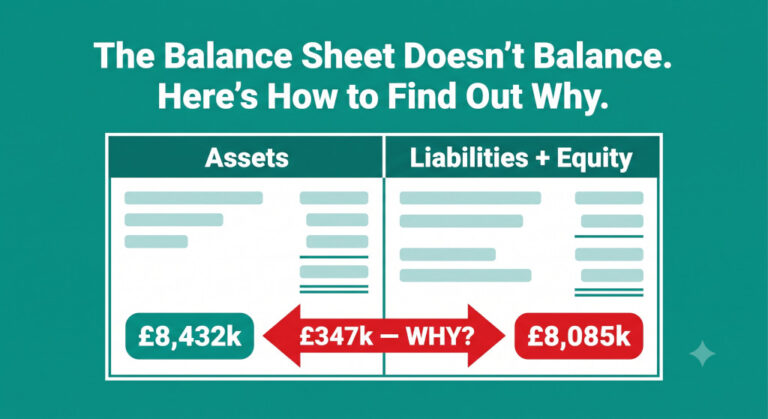
Why Doesn’t My Consolidated Balance Sheet Balance?
Nadia had been staring at the same number for forty minutes. Total assets: £8,432,000. Total liabilities plus equity: £8,085,000. The…
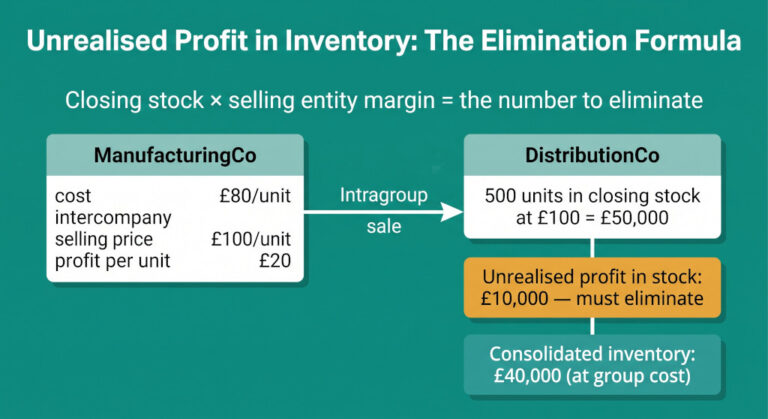
Unrealised Profit in Inventory: How to Eliminate Intragroup Margins From Closing Stock at Consolidation
When one group entity sells goods to another, the selling entity records a profit on that sale. From the perspective…