NCI
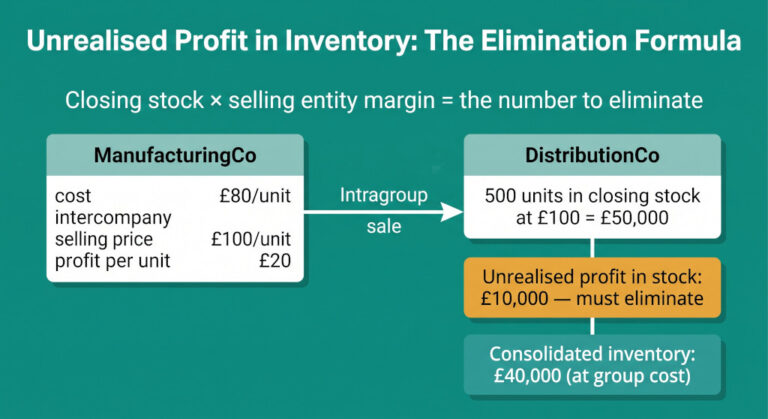
Unrealised Profit in Inventory: How to Eliminate Intragroup Margins From Closing Stock at Consolidation
When one group entity sells goods to another, the selling entity records a profit on that sale. From the perspective…
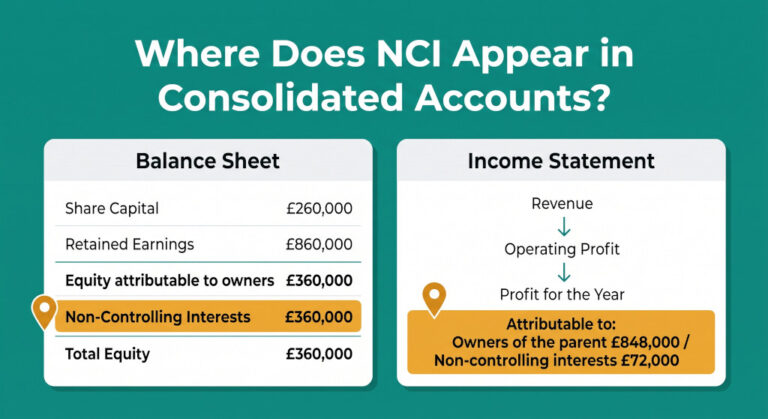
Non-Controlling Interest on the Balance Sheet and Income Statement: Where NCI Appears in Consolidated Financial Statements
Non-controlling interest appears in three places in a set of consolidated financial statements: in the equity section of the balance…
Intercompany Management Fee Eliminations: How to Remove Intragroup Charges From Consolidated Accounts
Management fees are one of the most common intragroup transactions in any multi-entity group — and one of the most…
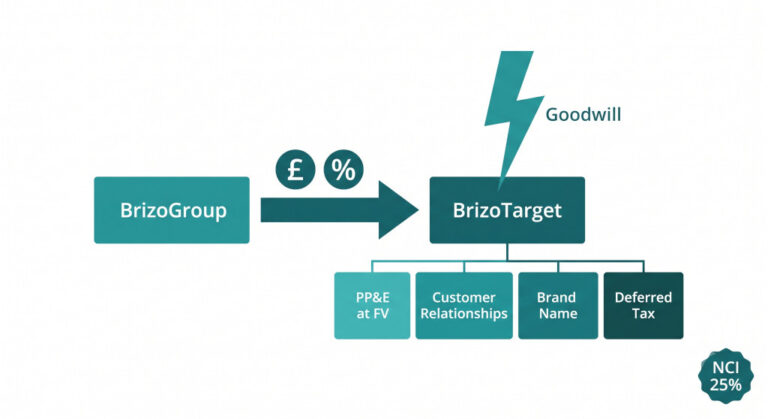
IFRS 3 Business Combinations: A Practical Guide for Multi-Entity Groups
Every consolidation begins with an acquisition. And every acquisition governed by IFRS starts with IFRS 3 Business Combinations — the standard that…
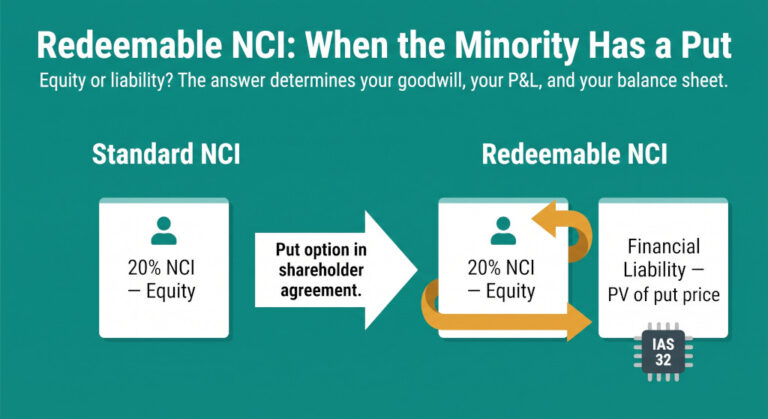
Redeemable NCI: How to Account for Put Options on Non-Controlling Interests
A non-controlling interest does not always sit quietly in equity. When the minority shareholder holds a contractual right to sell…
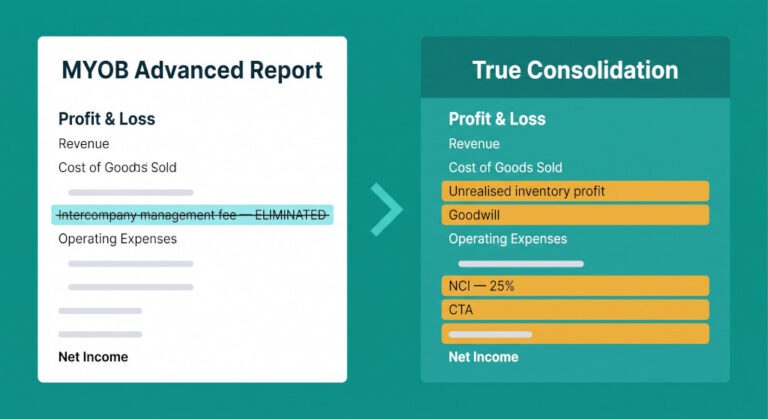
MYOB Advanced for Multi-Entity Groups: Limitations and What Finance Teams Use Instead
Priya had been the group financial controller at a mid-sized Australian services business for three years. The group had grown…
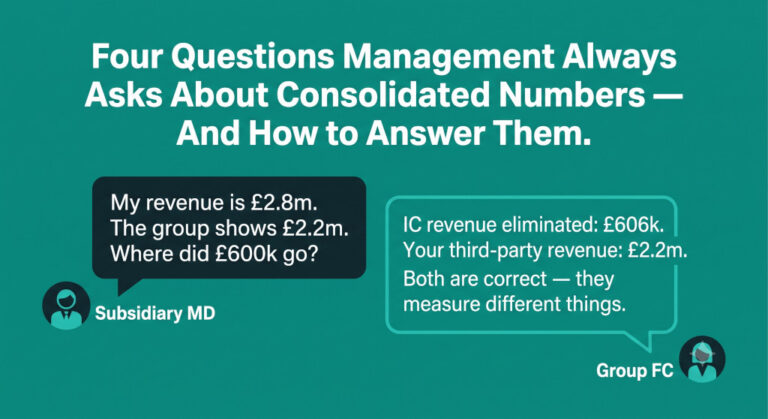
How to Explain Consolidated Variances to Management
The quarterly management pack went out on a Tuesday afternoon. By Wednesday morning, Clara’s inbox had four messages from four…
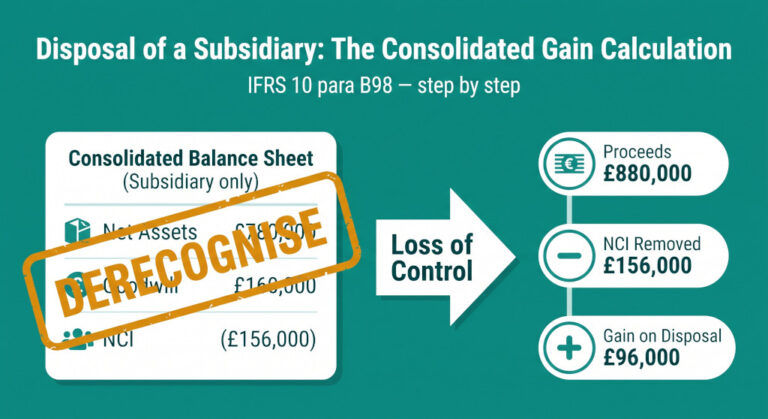
Disposal of a Subsidiary in Group Consolidation: How to Calculate the Gain, Derecognise the Net Assets, and Remove NCI
When a parent loses control of a subsidiary — whether through a full sale, a partial sale that drops below…
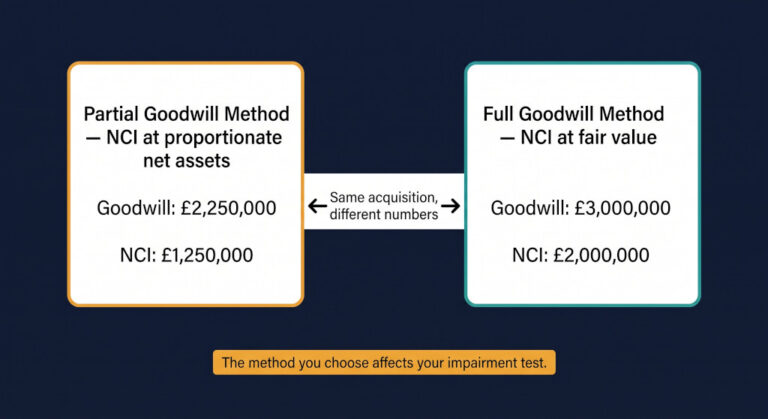
Full Goodwill vs Partial Goodwill: How Your NCI Measurement Choice Changes the Balance Sheet, the Impairment Test, and Who Absorbs the Loss
Helena is the group controller of Pinnacle Group, which has just acquired a 75% stake in Novum Ltd. The purchase…
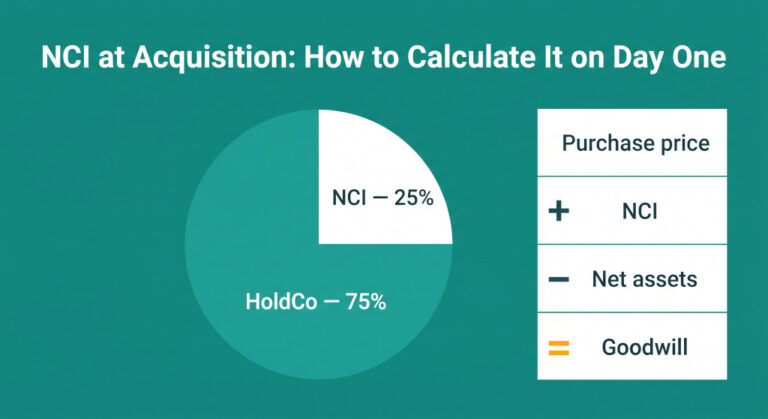
NCI at Acquisition: How to Calculate Non-Controlling Interest on the Date of Purchase
When HoldCo acquires 75% of SubCo, it controls SubCo from the acquisition date and must consolidate SubCo’s full balance sheet…